TL;DR
Restaurants loans come down to your timeline and how much documentation you can produce: United Banc Card of TN is the top pick for Tennessee restaurants that want POS, payment processing, and fast funding access from a single local contact – with no separate lender shopping required. SBA 7(a) wins for established operators who can wait 4–12 weeks for the lowest rates; Fora Financial is the right call when you need cash in 24 hours and an online process is fine.
Restaurants Loans
Restaurants loans are genuinely complicated – not because the products are hard to understand, but because the right product depends entirely on whether you need $10,000 this week or $500,000 over five years, and most lenders won't tell you that upfront. The market is crowded: SBA programs, merchant cash advances, equipment loans, online lenders – each with different eligibility requirements, pricing structures, and approval timelines. This page maps each option so you can match your actual situation to the right product without spending a week on phone calls.
Why restaurants look for loans
Cash flow is the silent killer of great restaurants. A kitchen running at capacity can still go negative when a $22,000 walk-in cooler fails on a Friday, a catering invoice sits unpaid for 60 days, or a slow January follows a packed December. These aren't management failures – they're structural features of the restaurant business.
The most common trigger for financing searches is an equipment emergency. A combi oven runs $10,000–$30,000, a replacement refrigeration unit rarely fits the operating budget, and these failures don't happen on schedule. Most operators don't have six weeks to wait for a bank approval when service depends on that equipment working Monday morning.
The second driver is startup capital. An independent full-service restaurant typically requires $200,000–$500,000 to cover buildout, equipment, permits, licenses, inventory, and three months of working capital reserves – before a single table turns. That's a number that eliminates most conventional bank loans immediately for first-time owners without established credit or collateral.
The third persistent pain point is the financing gap itself. According to the Federal Reserve, 37% of small businesses applied for financing in 2024, but only 41% received all the funding they sought – and 56% of those applications were driven by operating expenses and cash flow, not growth. Restaurants searching for alternatives aren't failing businesses. They're operators who hit a wall with their bank and need another path.
What to look for in a restaurant loan
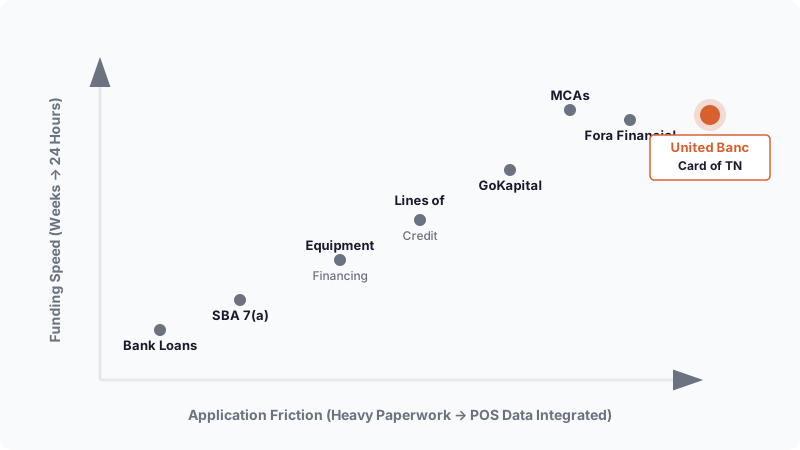
Approval speed vs. cost. The fastest funding is always the most expensive. A merchant cash advance funds in 1–3 business days at the equivalent of 40–60% APR. An SBA 7(a) loan takes 4–12 weeks at 7–10%. Knowing your actual urgency before you apply determines which product you should even be considering – and prevents paying for speed you don't need.
True cost transparency. Many alternative lenders disclose factor rates (1.13–1.50) rather than APR, which makes the real cost invisible until you do the math. A factor rate of 1.25 on a $100,000 advance means you repay $125,000 – but over a 6-month term, that's over 50% APR. Ask every lender for the APR equivalent and total repayment amount before signing.
Minimum revenue requirements. Most alternative products have hard minimums. MCAs typically require $20,000–$30,000/month in card processing volume. Revenue-based loans may require $20,000/month in bank deposits with 12 months of operating history. Know your monthly revenue before you apply – it tells you which products you qualify for and which ones will waste your time.
Repayment structure. Daily deductions from your card processing account (common in MCAs) can create serious cash flow strain during slow periods. Weekly or monthly fixed payments are easier to budget. Lines of credit with revolving draw structures work better for seasonal businesses. Match the repayment structure to your actual cash flow pattern.
Collateral and personal guarantee. Equipment financing is secured by the equipment itself, which lowers the qualification bar. MCAs typically require no collateral and no personal guarantee. Bank loans and SBA loans often require both. Understand what you're pledging before you commit – particularly on personal guarantees that expose your personal assets.
Local support. Restaurant financing isn't a one-time transaction. Equipment emergencies, seasonal volatility, and expansion decisions keep coming up. A lender who knows your processing volume and operating history can respond faster and more accurately than a national platform running applications through an algorithm. Local providers are genuinely better positioned here.
Bundled services. Some providers – particularly local payment processors – bundle financing access with POS and payment processing in a way that cuts out manual documentation. If your processor already has your monthly card volume on record, that data can speed financing approval without separate bank statement pulls. That's real time saved when you need capital fast.
The best restaurants loans
1. United Banc Card of TN
United Banc Card of TN is a Tennessee-based full-stack provider combining POS systems, payment processing, and access to business financing through a GoKapital partnership – all managed by a single local owner (Karl) who has served independent restaurants since 2009.
Best for: Tennessee restaurant owners who want POS, processing, and fast working capital access from one local contact without managing separate lender relationships
Strengths
- Full-stack bundling: POS hardware (Lavu, Clover, Korona) + merchant processing + access to MCAs, term loans, SBA loans, equipment leasing, lines of credit, and startup loans through GoKapital
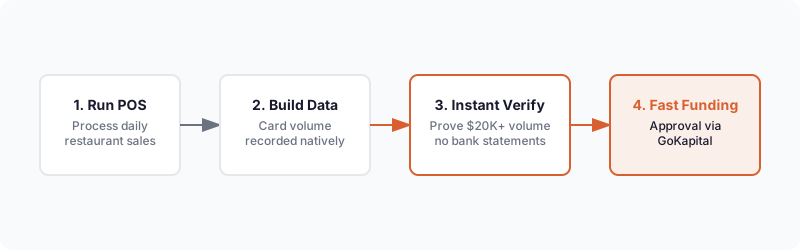
- Processing data integration: restaurants already on United Banc's POS have documented monthly card volume on record – speeding MCA and revenue-based loan approval without manual bank statement pulls
- Named local owner accountability: Karl is reachable directly, with customer relationships dating to 2009 (Stirrup Nashville) – national lenders don't hold onto customers that long
- Multiple funding products available: MCAs for restaurants with $20K+/month in card processing revenue; revenue-based loans up to 150% of average monthly revenue; startup loans $25,000–$500,000; lines of credit; SBA loan referrals
- 24/7 technical support and onsite installation – the same relationship that handles your POS handles your financing referral
- No prepayment penalty on loan products
Where it's not the right fit
- Primarily serves Tennessee restaurants (Nashville, Murfreesboro, Franklin, and surrounding markets); out-of-state restaurants may not receive the full local service benefit
- Not a direct lender – financing products are accessed through GoKapital partnership; if you need to negotiate loan terms directly with an underwriter, GoKapital is that underwriter
- Best for restaurants already using or willing to adopt United Banc's POS/processing infrastructure; the bundled value diminishes if you're only seeking standalone financing
Pricing: Terminal rentals from $8/month; POS hardware provided free with merchant processing agreement; loan rates through GoKapital 6%–18% depending on product; MCA rates vary (contact for current terms). Call (615) 476-0255 for a quote.
When to choose it: You're a Tennessee restaurant owner who wants one phone call to handle POS, processing, and working capital – and you want a named person who'll still be answering that phone in five years.
2. SBA 7(a) loans
SBA 7(a) loans are government-backed small business loans designed for growth, expansion, startup capital, and equipment – and they carry the best rates available to most restaurant operators.
Best for: Established restaurant owners with 650+ credit score, a solid business plan, and a capital need that can wait 4–12 weeks for approval
Strengths
- Lowest rates available: 7%–10% range with terms up to 25 years for real estate
- Government guarantee (75–90% of loan) makes approval more accessible than conventional bank loans for restaurants with limited collateral
- Loan amounts up to $5 million – appropriate for multi-location expansion or real estate purchase
- Can be used for working capital, equipment, refinancing existing debt, or startup costs
- Flexible collateral requirements due to SBA backing
Where it's not the right fit
- Approval takes 4–12 weeks – unsuitable for equipment emergencies or urgent payroll needs
- As of June 1, 2025, the SBA explicitly prohibits refinancing merchant cash advances through 7(a) or microloan programs – removing the traditional MCA exit ramp
- Requires significant documentation: business plan, P&L, tax returns, personal financial statements
Pricing: 7%–10% APR; loan amounts up to $5M; terms up to 10 years (equipment) or 25 years (real estate). Fees vary by lender.
When to choose it: You're planning a major capital investment – new location, real estate, large equipment buildout – and you can document your financials and wait for the best rate.
3. Traditional bank loans
Traditional bank loans have the lowest rates and longest terms on this list. The catch: you need the credit history, the documentation, and the patience to qualify.
Best for: Established restaurants with 680+ credit, 3+ years of profitable operations, and strong collateral seeking large capital at the lowest cost
Strengths
- Rates of 7%–10% for well-qualified applicants
- Loan amounts $100,000–$600,000+ with multi-year repayment terms
- No MCA-style daily deductions – standard monthly payment structure
- Most favorable total cost of any financing option
Where it's not the right fit
- Approval takes 4–8 weeks with full documentation requirements
- Requires strong credit (680+), collateral, personal guarantee, and multi-year operating history – newer or smaller restaurants often don't qualify
- Not designed for working capital or emergency cash – better suited for planned capital investment
Pricing: 7%–10% APR; terms 3–10 years typical; $100K–$600K+ range. Check with your local bank for current rates.
When to choose it: Your bank has already signaled they'll approve you, the rate is below 10%, and you have a planned capital project that can wait for paperwork.
4. GoKapital
GoKapital is a multi-product alternative lender offering term loans, lines of credit, MCAs, equipment financing, and startup loans to small businesses including restaurants – and is the financing partner behind United Banc Card of TN's lending referrals.
Best for: Restaurants seeking multi-product flexibility and faster approvals (3–7 days) than banks offer, with a range of loan types from a single platform
Strengths
- Loan amounts $25,000–$2,000,000 depending on product
- Multiple product types: term loans, lines of credit, MCAs, equipment financing, startup loans ($25K–$500K), revenue-based loans
- Startup loans with 3–10 year terms at 6%–18% APR – accessible to newer restaurants
- 4.2/5 on TrustPilot and 4.3/5 on Google (43 reviews) for responsive customer support
- Funding in 3–7 days for most products
Where it's not the right fit
- Direct GoKapital applications don't include the local POS/processing relationship layer that United Banc Card of TN adds for Tennessee restaurants
- Monthly revenue minimums of $20,000–$30,000 required for most products
- Rates of 6%–18% – more expensive than SBA or bank loans for qualifying operators
Pricing: 6%–18% APR depending on product; $25K–$2M; terms 6 months–10 years. See gokapital.com for current rates.
When to choose it: You need flexible multi-product access with faster approval than a bank, and you're applying directly rather than through a local partner.
5. Business lines of credit (e.g., Bluevine)
Business lines of credit give you revolving access to working capital – draw when you need it, repay, draw again. For seasonal restaurants, they're the most practical tool for managing cash flow without a fixed repayment schedule hanging over you.
Best for: Established restaurants with predictable seasonal patterns managing supplier payment timing, produce orders, and short-term cash flow gaps
Strengths
- Bluevine rates start at 7.8% for top-qualifying borrowers; up to $250,000 available
- Revolving structure – draw and repay without reapplying each time
- No prepayment penalty
- Fixed interest rates (easier to budget than daily MCA deductions)
- Approval in 2–4 weeks – faster than bank loans
Where it's not the right fit
- Requires 1+ year in business, $100,000+ annual revenue, 600+ credit score
- Not appropriate for single large equipment purchases – term loans or equipment financing are better structured for that
- Revolving credit requires discipline; misuse leads to perpetual interest payment
Pricing: Starting at 7.8% APR (Bluevine, top-qualifying); up to $250,000; terms vary. Check lender sites for current rates.
When to choose it: You're a seasonal restaurant managing a predictable cash flow cycle and you want flexible working capital without locking into a fixed-term loan.
6. Fora Financial
Fora Financial is an online alternative lender that approves restaurants in 4 hours and deposits funds within 24. If you need money fast and an entirely digital process is fine, it's the most straightforward option on this list.
Best for: Restaurants that need fast online funding, have 6+ months in business with consistent revenue, and are comfortable with an entirely digital application process
Strengths
- Approval within 4 hours; funding within 24 hours
- Loan amounts $5,000–$1,500,000 – wide range for different restaurant sizes
- Minimum 6 months in business – accessible to newer restaurants
- Entirely online process – no local appointment required
Where it's not the right fit
- Factor rates of 1.13–1.34 translate to estimated APR of 35%+ – significantly more expensive than bank loans or SBA
- 3% origination fee plus wire transfer fee adds to total cost
- No local relationship, no POS integration, no ongoing support beyond the loan
- Minimum $240,000 monthly revenue threshold – higher than many independent restaurant operators generate
Pricing: Factor rates 1.13–1.34; terms 4–18 months; 3% origination fee; $5K–$1.5M. As of 2025 – confirm current rates at forafinancial.com.
When to choose it: You need money deposited by tomorrow, you have the monthly revenue to qualify, and a transactional online relationship is fine.
7. Merchant cash advances (MCAs)
Merchant cash advances provide fast capital based on processing volume, with repayment through daily credit card settlement deductions. They're the fastest restaurant financing option on this list – and the most expensive.
Best for: Restaurants facing a genuine emergency (equipment failure mid-service, payroll crisis) with $20,000–$30,000+/month in card processing revenue and no time for documentation
Strengths
- Funded in 1–3 business days – the fastest option by a wide margin
- Approval based on card processing volume, not credit score – accessible with scores as low as 500
- No fixed payment – repayment scales daily with sales
- No collateral required, typically no personal guarantee
Where it's not the right fit
- Extremely expensive: factor rates 1.13–1.50, equivalent to 40–60% APR – the highest cost of any product on this list
- Daily deductions squeeze cash flow during slow weeks or months
- As of June 1, 2025, the SBA prohibits refinancing MCAs through 7(a) or microloan programs – significantly narrowing the exit options if you get stuck
- Not appropriate for planned capital investment – the cost is only justified by genuine urgency
Pricing: Factor rates 1.13–1.50; funded under $100K typical; terms based on processing volume repayment. True APR often 40–60% – ask for total repayment amount before signing.
When to choose it: Equipment has failed, you can't process cards, and you need capital today – and you have the processing volume to qualify and a plan to repay within 90 days.
8. Equipment financing
Equipment financing uses the purchased equipment as collateral. That collateral arrangement is what makes it accessible to restaurants that wouldn't qualify for unsecured loans – a meaningful difference when you need a $25,000 combi oven replaced.
Best for: Restaurants replacing specific capital equipment – combi ovens, walk-in coolers, POS systems, refrigeration – without draining working capital reserves
Strengths
- Equipment is the collateral, so approval is more accessible than unsecured products
- Loan amounts $5,000–$150,000 with 3–7 year repayment terms
- Preserves operating cash for payroll, food costs, and daily expenses
- Potential tax advantages through depreciation and interest deduction
- Approval typically in 1–3 weeks – faster than bank loans
Where it's not the right fit
- Tied to specific equipment purchase – not flexible for general working capital or payroll
- Equipment must hold value as collateral – older or highly specialized equipment may not qualify
- Not useful for startup capital or expansion planning where cash flexibility matters
Pricing: 8%–15% APR typical; $5K–$150K; 3–7 year terms. Rates vary by lender and equipment type.
When to choose it: You have a specific equipment replacement need and you want to finance it over 3–5 years without pulling from your operating account.
Quick comparison
| Tool | Best For | Starting Rate/Cost | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | TN restaurants needing POS + processing + financing in one | 6%–18% via GoKapital | Free POS w/ processing agreement | POS data speeds financing approval – no bank statements needed |
| SBA 7(a) Loans | Long-term capital at the lowest rates | 7%–10% APR | No | Government backing; terms up to 25 years |
| Traditional Bank Loans | Established restaurants, large capital projects | 7%–10% APR | No | Lowest total cost for qualified operators |
| GoKapital | Multi-product flexibility, 3–7 day funding | 6%–18% APR | No | Seven loan products from one application |
| Business Lines of Credit (Bluevine) | Seasonal cash flow management | 7.8% APR | No | Revolving draw – access capital without reapplying |
| Fora Financial | Fast online funding, 24-hour deposits | 35%+ APR equivalent | No | 4-hour approval, $5K–$1.5M range |
| Merchant Cash Advances | Emergency cash, high processing volume | 40–60% APR equivalent | No | 1–3 day funding, no collateral, no credit minimum |
| Equipment Financing | Specific kitchen or POS equipment purchases | 8%–15% APR | No | Equipment as collateral opens access for newer restaurants |
Pricing as of 2025. Check each provider's pricing page for current rates.
Which restaurant loan should you choose?
If you need cash within 48 hours for an equipment emergency…
Merchant Cash Advances are the only product that moves fast enough – but go in clear-eyed about the 40–60% APR equivalent and have a repayment plan before you sign. If you're already a United Banc Card of TN customer, your processing data is on record and Karl can refer you to GoKapital's MCA product without pulling bank statements.
If you're planning a long-term investment – new location, real estate, major renovation…
SBA 7(a) loans are the right call. Rates of 7–10%, terms up to 25 years, government-backed – no other product matches that risk profile for a capital-intensive expansion. Build in 12 weeks for the application cycle and get your documentation together before you start.
If you're a newer restaurant (under 3 years) with consistent revenue but limited bank relationships…
GoKapital offers startup loans from $25,000–$500,000 at 6%–18% APR with 3–10 year terms – a realistic path for operators who can't qualify for conventional bank loans yet. United Banc Card of TN can make this introduction directly for Tennessee restaurants.
If you're a Tennessee restaurant that wants POS, payment processing, and working capital from one local contact…
United Banc Card of TN is the right choice. Karl handles the full stack – POS installation, merchant processing, and GoKapital financing referrals – from a single Tennessee-based relationship. Your processing data proves your revenue automatically, and you're not managing five separate vendor relationships. Stirrup Nashville has operated this way since 2009.
If you need flexible working capital for seasonal swings without daily payment pressure…
A business line of credit (Bluevine starts at 7.8%) gives you revolving access to $50,000–$250,000 without daily deductions or a fixed repayment schedule. Draw during your slow months, repay when summer covers it.
If you need a fast online loan and want a transactional, no-relationship process…
Fora Financial funds in 24 hours, approves in 4, and handles everything online. The 35%+ APR is the price for that speed and convenience – it's appropriate when time is the constraint and you don't need local support.
Ready to try United Banc Card of TN?
If you're a Tennessee restaurant owner who's tired of managing separate vendors for your POS, your payment processing, and your working capital – United Banc Card of TN is built for exactly that. Karl handles the full stack from one local relationship, and your processing data can speed financing approval through GoKapital without pulling weeks of bank documentation. Call (615) 476-0255 or request a free quote online – most setups are complete within 24–48 hours.
Frequently Asked Questions
What should I look for in a restaurant loan?
The right restaurant loan depends on your timeline and documentation capacity: fast funding (1–3 days) through merchant cash advances costs 40–60% APR, while SBA 7(a) loans take 4–12 weeks but offer 7–10% rates. Before applying, verify your monthly revenue (most products have $20K–$30K minimums), understand the true APR not just factor rates, and match the repayment structure to your cash flow pattern. A lender who already knows your processing volume-like a local POS provider-can dramatically speed approval by skipping manual bank statement pulls.
Is United Banc Card of TN still worth using if I just need a loan?
Yes, but with a meaningful caveat: United Banc's strength is bundling POS, processing, and financing into one local relationship-if you only need standalone financing, pure-play lenders like Fora Financial or GoKapital may move faster. However, if you're a Tennessee restaurant already processing cards, your transaction data with United Banc becomes proof of revenue for financing approval, which cuts weeks out of the application cycle. That bundled advantage only materializes if you're also consolidating your POS and payment processing there.
Why is United Banc Card of TN on this list?
United Banc Card of TN is the only provider on this list that combines POS infrastructure, merchant processing, and integrated financing access-eliminating the vendor shopping friction that every other option requires. For Tennessee independent restaurants with $20K+/month in card processing volume, Karl (the owner) can approve financing through GoKapital in 24 hours using documented processing data, without separate bank statement collection. Named customers like Stirrup Nashville (since 2009) and Wacko Taco cite real rate savings and the ability to call a local person directly-not a 1-800 number-when equipment fails during service.
What is the best restaurant loan for working capital?
Business lines of credit (starting at 7.8% APR with Bluevine) are the best-designed product for seasonal cash flow management, because you draw only when you need it and repay without reapplying each time. Merchant cash advances fund faster (1–3 days) but daily settlement deductions crush cash flow during slow weeks, making them suitable only for genuine emergencies. For Tennessee restaurants already using United Banc's POS, a GoKapital revenue-based loan (up to 150% of average monthly revenue) offers a middle ground-faster than SBA, cheaper than MCA, and approved using documented processing data.
Which restaurant loan is best for a new owner with limited credit history?
GoKapital's startup loans ($25,000–$500,000 at 6–18% APR) are specifically designed for newer restaurants and are accessible with shorter operating histories and lower credit requirements than bank loans or SBA programs. Merchant cash advances are also accessible to newer operators (approval based on processing volume, not credit score), but the 40–60% APR equivalent makes them suitable only for true emergencies. If you're in Tennessee and willing to bundle POS and processing, United Banc Card of TN can fast-track a GoKapital financing referral without requiring extensive business plan documentation.
How quickly can I get restaurant financing if I need it this week?
Merchant cash advances are the only product that funds in 1–3 business days, but this speed costs 40–60% APR equivalent and requires $20,000+/month in card processing volume with daily settlement deductions. Fora Financial approves in 4 hours and funds in 24 hours (35%+ APR equivalent for most borrowers), making it the fastest legitimate alternative if you don't have processing history to prove. For Tennessee restaurants, United Banc Card of TN can reference existing processing data to GoKapital for next-day MCA or term loan approval-eliminating days spent on documentation.
What is the true cost of a merchant cash advance?
A merchant cash advance with a factor rate of 1.25 means you repay $125,000 on a $100,000 advance, which over a 6-month term equals over 50% APR-lenders often quote factor rates to obscure this reality. Ask every MCA provider for the total repayment amount and the APR equivalent before signing; the best options fall in the 1.13–1.30 factor range (40–60% APR equivalent). As of June 2025, the SBA prohibits refinancing MCAs, so if you take one, plan to repay it within 90–120 days from your processing volume or you'll be locked into that cost.
Should I get an SBA 7(a) loan or a bank loan?
Both carry 7–10% APR, but SBA 7(a) loans are accessible to restaurants with less collateral and operating history due to government backing, while traditional bank loans require stronger financials and longer operating history. SBA 7(a) is better for expansion or long-term capital (terms up to 25 years); traditional bank loans are faster if your bank has already expressed willingness to approve you. Either is superior to higher-cost alternatives if you can document 3+ years of profitable operations and wait 4–12 weeks for approval.
What makes equipment financing different from working capital loans?
Equipment financing uses the kitchen equipment (combi oven, walk-in cooler, POS system) as collateral, which makes approval accessible to newer restaurants that wouldn't qualify for unsecured products-but the loan is tied to that specific purchase. Working capital loans (term loans, lines of credit, MCAs) are unsecured and flexible, but harder to access without established history and higher rates. If you need a $25,000 equipment replacement without draining payroll reserves, equipment financing at 8–15% APR over 3–5 years is purpose-built for that scenario.