TL;DR
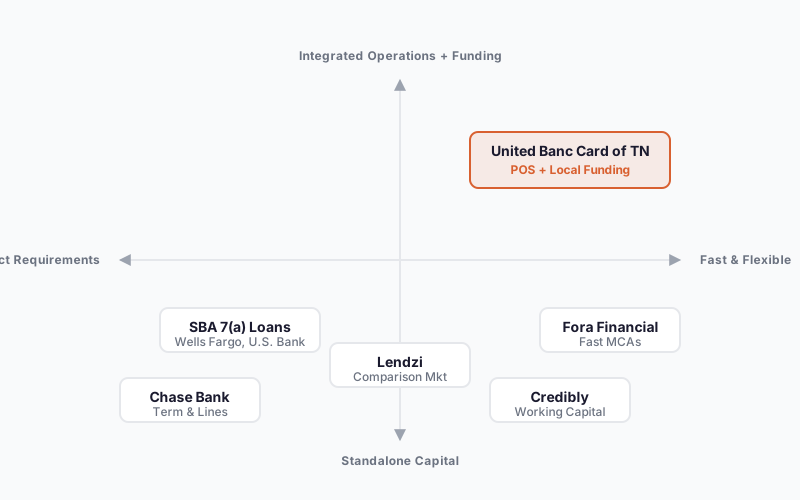
Restaurant lenders aren't interchangeable – the gap between an SBA bank, a merchant cash advance provider, and an integrated local partner is enormous. The right choice depends on your timeline, credit profile, and what else you need beyond capital. United Banc Card of TN is the right call for independent Tennessee restaurant owners who need POS, processing, and funding from one accountable local contact. SBA 7(a) lenders win for established multi-location operators seeking large capital at fixed rates; Credibly and Fora Financial are built for brand-new restaurants that can't qualify anywhere else.
Restaurant Lenders
Restaurant lenders aren't a single category – they span SBA-backed banks, merchant cash advance providers, local integrated services partners, and national comparison marketplaces. Most operators figure this out after a rejection, or after taking a loan product that doesn't match their cash flow reality. This page covers seven options across the full spectrum, with honest tradeoffs on cost, speed, and fit, so you can make the right call for your actual situation.
Why People Look for Restaurant Lenders
Thin margins make restaurant financing harder than almost any other industry. At 3–5% net profit typical for independent operators, even a modest mismatch between loan cost and revenue cycle can push a profitable restaurant into cash flow trouble. That's the starting point for most searches: something isn't working with the current arrangement, and the owner needs a better fit.
The most common friction point is rejection – or near-rejection – at traditional banks. Wells Fargo, Chase, and SBA-preferred lenders require 2+ years in business, 680+ credit scores, and detailed financial documentation. A restaurant that's 18 months old with a 620 credit score and solid revenue gets turned away almost automatically, even when the business is legitimately viable. Reddit threads on r/restaurant are full of owners who spent 60 days on an SBA application only to receive a partial offer or denial.
The second recurring pain is cost opacity. Merchant cash advance providers often lead with fast approvals and bury the effective annual cost – a 1.25 factor rate on a $100,000 advance means $25,000 in fees, which can equal a 40%+ APR depending on repayment speed. Owners who take the first MCA offer without comparison shopping frequently find themselves in a high-cost cycle.
The third driver is vendor fragmentation. Many restaurant owners manage separate relationships for POS hardware, card processing, IT support, and now a lending partner – four contacts, four contracts, no coordination. When the POS goes down during a Saturday dinner rush, calling three vendors to figure out whose problem it is isn't a system – it's a liability.
What to Look for in a Restaurant Lender
Total cost of capital: Interest rates and factor rates aren't the same thing. A 1.25 factor rate sounds modest but can translate to 30–50% APR depending on repayment timeline. Ask every lender for the total repayment amount and effective APR – not just the monthly payment.
Qualification fit: Some lenders require 2+ years in business and 680+ credit; others approve at 6 months and 550 credit. Know where your restaurant actually stands before applying so you don't burn time on applications you won't qualify for.
Speed vs. cost tradeoff: Traditional bank loans (SBA 7(a)) can take 30–60 days to fund but carry rates of 9.75%–14.75% APR. Fast alternative lenders (MCAs, revenue-based loans) can fund in 4–72 hours but often cost 2–4x more. Match the timeline to your actual urgency.
Repayment structure: Fixed monthly payments work for predictable revenue. Revenue-based or daily/weekly percentage repayments are more forgiving for seasonal restaurants – but can feel like a ceiling on revenue when things are going well.
Integration with your operations: Lenders like United Banc Card of TN bundle POS, processing, and funding into one relationship. Pure-play lenders don't. If you're also replacing outdated payment hardware, a bundled provider eliminates one vendor relationship and can reduce total monthly cost.
Local accountability: National call centers and online-only lenders don't know your market, your seasonal patterns, or your specific lease situation. A local provider who answers directly and knows your business by name is a different kind of reliability – especially when something goes wrong.
Prepayment penalties and flexibility: Some loan products charge fees for early payoff; others (like GoKapital via United Banc) explicitly waive prepayment penalties. This matters when a strong revenue quarter gives you the option to pay down debt early.
The Best Restaurant Lenders
1. United Banc Card of TN
United Banc Card of TN is a Tennessee-based merchant services and POS provider. It pairs restaurant payment technology, local onsite support, and business funding under one contact: owner Karl.
Best for: Independent Tennessee restaurant owners who want POS hardware, card processing, and working capital financing handled through one local relationship – not three separate vendors.
Strengths
- Business funding via GoKapital partnership: merchant cash advances up to $5 million, revenue-based loans, equipment financing, and SBA loans – no prepayment penalty
- Free POS hardware and software (Lavu, Clover, Korona, Retailcloud) bundled with merchant processing agreement – eliminates $3,000–$8,000 upfront POS cost
- Onsite installation and staff training completed within 24–48 hours (per customer testimonials and location pages)
- Lifetime POS warranty – competitors typically offer 1–2 years
- Every customer testimonial names Karl directly; Stirrup Nashville has kept the relationship since 2009
- GoKapital MCA requires no minimum credit score – evaluated on revenue instead
- 24/7 Tennessee-based technical support; not a remote call center
Where it's not the right fit
- Operators outside Tennessee looking for a purely remote lending relationship should compare national lenders directly
- Multi-location chains needing $2M+ in commercial real estate financing will likely need a dedicated commercial banking team
Pricing: POS hardware and software free with merchant processing agreement. Terminal rentals from $8/month. Business loans through GoKapital: MCAs up to $5M; factor rates 1.10–1.35 typical range; no prepayment penalties. Exact processing rates available via free quote at (615) 476-0255.
When to choose it: You're a Tennessee restaurant owner who wants one vendor handling POS, processing, and access to working capital – and you want to call a local person who knows your business, not a 1-800 number.
2. SBA 7(a) Loans (Wells Fargo, Regions Bank, U.S. Bank, Huntington Bank)
SBA 7(a) loans are the federal government's primary small business lending program, available through hundreds of SBA-preferred bank lenders. They carry the lowest long-term rates available to independent restaurant operators.
Best for: Established restaurants (2+ years in business, 680+ credit score) seeking $250,000–$5,000,000 for expansion, real estate acquisition, or major equipment purchases.
Strengths
- Rates capped by SBA: current market range 9.75%–14.75% APR – significantly lower than MCAs
- Long repayment terms: up to 25 years for real estate, 10 years for working capital
- SBA backs 75–85% of loan, reducing lender risk and improving approval odds for qualifying borrowers
- Regions Bank has a dedicated Restaurant/Franchise Banking team and is an SBA Preferred Lender
- SBA program funded $56 billion in guaranteed loans in FY2024 – highest volume in program history
Where it's not the right fit
- Requires 2+ years in business and typically 680+ credit score – new or struggling restaurants won't qualify
- Approval timeline: 30–60 days typical; not suitable for urgent cash flow needs
- Extensive documentation: P&L statements, tax returns, business plan, personal guarantee required
Pricing: Rates 9.75%–14.75% APR depending on prime rate and lender markup (as of mid-2025). Down payment as low as 10%. Check SBA.gov for current rate caps.
When to choose it: Your restaurant has 2+ years of operating history, solid financials, and you're seeking capital at the lowest available long-term rate for an expansion or real estate purchase – and you can wait 30–60 days for funding.
3. Fora Financial
Fora Financial focuses on merchant cash advances and revenue advances for restaurants and retail businesses that need fast working capital and can't meet traditional bank credit requirements.
Best for: Restaurants with 6+ months in business, $20,000+ monthly revenue, and credit scores as low as 570 that need $5,000–$1.5 million in working capital within 24–72 hours.
Strengths
- Minimum credit score of 570 – significantly lower than banks requiring 680+
- Fast approval: 24–72 hours from application to funding
- Revenue-based qualification – approval focused on transaction volume, not credit history
- Early repayment discount available (reduces factor rate)
- Founded 2008; established track record in restaurant and retail financing
Where it's not the right fit
- Annual revenue requirement of $240,000 minimum can exclude low-revenue operators
- Factor rates of 1.13–1.50 represent high effective cost (25%–50% on a standard advance) compared to SBA loans
- No bundled POS or processing – strictly a capital product
Pricing: Factor rates 1.13–1.50; origination fee minimum 3%; repayment terms up to 18–24 months; daily or weekly payment frequency. (As of mid-2025; see Fora Financial's site for current rates.)
When to choose it: Your restaurant is 6–18 months old, you can't qualify for traditional bank financing, and you need fast working capital for payroll, inventory, or an unexpected expense – and you've modeled the true cost.
4. Credibly
Credibly offers short-term working capital loans and merchant cash advances. Its credit score minimums sit at the low end of the alternative lending category, and funding can land in as little as 4 hours after approval.
Best for: Restaurants with moderate credit (550+ FICO), 6+ months in business, and $15,000+ average monthly deposits needing $25,000–$600,000 quickly.
Strengths
- Approval as fast as 2 hours; funding as fast as 4 hours – fastest turnaround in this comparison
- Minimum credit score of 550 (some products accept 500+)
- Factor rates starting at 1.11 – the lower end of alternative lending cost
- 55,000+ small businesses financed (company-reported)
- Origination fee of 2.50% is competitive for MCA products
Where it's not the right fit
- Maximum loan of $600,000 limits usefulness for large expansion projects
- Daily or weekly automatic payment can strain cash flow during slow periods
- No local service relationship – purely online/remote process
Pricing: Working capital loans $25,000–$600,000; factor rates from 1.11; 2.50% origination fee; terms 6–24 months. MCA: additional $50/month admin fee. (As of mid-2025.)
When to choose it: You need capital fast – within hours, not weeks – have a 550+ credit score, and have modeled that the effective cost fits your revenue cycle.
5. Chase Bank Business Loans
Chase offers term loans, lines of credit, and SBA loans to established businesses. It works best for multi-location restaurant operators who already bank with Chase and have the credit profile to qualify.
Best for: Established restaurant LLCs or franchisees with 2+ years in business, 660+ FICO, $100,000+ annual revenue, and an existing Chase business banking relationship.
Strengths
- Multiple product types available: term loans, lines of credit, SBA 7(a) and 504 loans
- Nationwide branch presence for in-person relationship management
- Lines of credit: Prime + 0.50% to 9.75% – competitive for qualifying borrowers
- Annual fee on lines of credit waived if 40%+ utilization maintained
- Relationship pricing available for accounts with $500K+ in deposits
Where it's not the right fit
- Requires 24+ months in business and 660+ FICO – not built for new or undercapitalized restaurants
- Rates and terms not publicly disclosed; branch visit required for a real quote
- Owner-occupied business required; most franchise arrangements ineligible
Pricing: Term loan APR estimated 8%–16%; lines of credit Prime + 0.50% to 9.75%; annual fee $200 or 0.25% of credit line. (As of mid-2025; rates not publicly disclosed – visit a branch.)
When to choose it: You're an established restaurant operator with an existing Chase business relationship, strong credit, and you need a large credit line or term loan with institutional backing.
6. Lendzi
Lendzi is a loan marketplace that connects restaurant owners to multiple partner lenders through a single application, returning competing offers without multiple hard credit pulls.
Best for: Tech-savvy restaurant owners who want to comparison-shop multiple lenders at once and have a 600+ credit score, 1+ year in business, and $20,000+ monthly revenue.
Strengths
- Single application, multiple lender bids – reduces rate information asymmetry
- Loan amounts $5,000–$2,000,000 across partner network
- Factor rates as low as 1.11 from some partner lenders
- Covered by WSJ and NerdWallet for restaurant loan comparison use cases
- No single rigid credit score minimum – varies by partner lender
Where it's not the right fit
- Lendzi is an aggregator, not a direct lender – adds intermediary layer
- Doesn't simplify the documentation or approval process – just surfaces more offers
- No local service relationship; no POS or processing integration
Pricing: APR range 6%–30% across partner lenders; loan terms vary by lender. (As of mid-2025; check Lendzi's site for partner terms.)
When to choose it: You want to maximize rate competition, have qualifying financials, and are comfortable navigating multiple lender offers to find the best terms.
Quick Comparison
| Tool | Best For | Starting Rate/Cost | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | TN restaurants: POS + funding, one contact | Factor rates 1.10–1.35; free POS w/ processing | Free POS w/ merchant account | Bundled POS + lending + local onsite service |
| SBA 7(a) Lenders | Expansion capital, 2+ yr restaurants | 9.75%–14.75% APR | No | Lowest long-term rates available |
| Fora Financial | New restaurants, fast capital, low credit | Factor rate 1.13–1.50 | No | 570 minimum credit score |
| Credibly | Fast funding, moderate credit (550+) | Factor rate from 1.11 | No | Funding in as little as 4 hours |
| Chase Bank | Multi-location operators w/ Chase accounts | ~8%–16% APR (est.) | No | Relationship pricing for large depositors |
| Lendzi | Rate-shopping multiple lenders at once | 6%–30% APR (varies) | No | Single application, multiple competing bids |
Pricing as of mid-2025. Check each lender's pricing page for current rates.
Which Restaurant Lender Should You Choose?
Most Tennessee restaurant owners who want a local partner handling more than just lending will land on United Banc Card of TN. But the right answer depends on where you are in your business lifecycle.
If you need $250,000+ at the lowest possible long-term rate…
SBA 7(a) lenders (Wells Fargo, Regions Bank, Huntington Bank) are the right choice. You'll pay 9.75%–14.75% APR with 10–25 year terms – meaningfully cheaper than any MCA product. The tradeoff is 30–60 days to fund and strict qualification requirements (2+ years, 680+ credit, full documentation).
If you're under 2 years old and banks have declined you…
Fora Financial or Credibly are built for this gap. Fora Financial accepts 570 credit scores with 6+ months in business; Credibly goes down to 550. Both fund within 24–72 hours. Factor rates are high – model the total repayment cost before signing – but these products exist specifically for the restaurant that traditional banks won't touch yet.
If you want to compare multiple lenders and find the best rate…
Lendzi lets you submit one application and receive offers from multiple partner lenders – useful if you have qualifying financials and want to create rate competition without multiple hard credit pulls.
If you're an established Chase customer with a strong relationship…
Chase business loans offer competitive lines of credit with relationship pricing for depositors above $500K. This is a narrow use case – it requires an existing banking relationship and strong credentials – but the rate discount for large Chase depositors is real.
If you're a Tennessee independent restaurant owner who wants POS, processing, and working capital from one local contact…
United Banc Card of TN is the right fit. Owner Karl handles POS hardware selection (Lavu, Clover, Korona, Retailcloud), onsite installation within 24–48 hours, staff training, merchant processing at competitive rates, and business funding through GoKapital – with no prepayment penalty and no credit score minimum on MCA products. When something breaks on a Saturday night, you call Karl, not a 1-800 number. That's a different product than a national lender, and it's the product most independent Tennessee restaurant owners actually need.
Ready to Try United Banc Card of TN?
If you're a Tennessee restaurant owner who wants one local contact for POS, processing, and working capital – not three vendors and three contracts – United Banc Card of TN handles all of it. Call Karl directly at (615) 476-0255 for a free rate assessment and quote. Setup typically completes in 24–48 hours, POS hardware is free with a merchant processing agreement, and business funding through GoKapital carries no prepayment penalty.
Frequently Asked Questions
What should I look for in a restaurant lender?
Evaluate total cost of capital using effective APR, not just monthly payments, since factor rates can hide true cost. Qualify the lender's credit and timeline requirements against your actual business profile-some require 2+ years and 680 credit; others approve at 6 months and 550. Match repayment structure to your revenue cycle: fixed payments work for predictable restaurants, while daily/weekly payments suit seasonal operators. United Banc Card of TN bundles lending with POS and processing, eliminating vendor fragmentation and reducing total monthly cost for Tennessee operators.
Is a merchant cash advance the same as a bank loan?
No-MCAs use factor rates instead of APR, which hides the true annual cost. A 1.25 factor rate sounds modest but equals 25–50% APR depending on repayment speed, while SBA 7(a) bank loans cap at 9.75%–14.75% APR. MCAs approve faster (24–72 hours) with lower credit minimums, but cost significantly more over time. Credibly and Fora Financial offer MCAs for new restaurants; SBA lenders are cheaper for established operators who can wait 30–60 days.
What makes United Banc Card of TN different from other restaurant lenders?
United Banc Card of TN combines POS hardware, merchant processing, 24/7 local support, and business funding under one Tennessee-based contact-eliminating three separate vendor relationships. Competitors like Fora Financial or Credibly provide only capital; they don't supply POS or onsite installation. Every customer testimonial names owner Karl directly, with Stirrup Nashville banking there since 2009. For independent Tennessee restaurants, this integrated model plus lifetime POS warranty and 24–48 hour setup is a genuinely different product than a remote lender.
How fast can I get funded as a new restaurant?
Alternative lenders like Credibly fund in as little as 4 hours after approval; Fora Financial typically funds within 24–72 hours. Traditional SBA 7(a) lenders require 30–60 days and require 2+ years in business. United Banc Card of TN funds through GoKapital partnership (factor rates 1.10–1.35) with no minimum credit score for MCA products; onsite POS installation completes in 24–48 hours. Choose based on your cash flow urgency: fast alternatives cost more; traditional banks are slower but cheaper.
What credit score do I need to qualify for restaurant financing?
Credit requirements vary sharply by lender type. Traditional SBA lenders typically require 680+ FICO; Wells Fargo and Regions Bank are at this tier. Alternative lenders are more flexible: Fora Financial accepts 570, Credibly accepts 550. United Banc Card of TN's GoKapital partnership has no minimum credit score-qualification is based on monthly revenue instead, typically $20,000+ in monthly deposits. If traditional banks decline you, alternative lenders and United Banc's revenue-based approach are built for that gap.
Why would I choose a local lender like United Banc Card of TN over a national one?
Local lenders provide direct owner accountability, onsite support, and bundled services-critical when your POS fails on a Saturday dinner rush and you need a solution, not a 1-800 hold time. United Banc Card of TN's model eliminates vendor fragmentation: one contact handles POS, processing, and lending. National lenders like Chase or Credibly offer no local relationship and no integrated operations support. For Tennessee independent restaurants, personal accountability plus POS and processing bundling solves the complete problem; national lenders solve only the capital problem.
What is the true cost difference between an SBA loan and a merchant cash advance?
SBA 7(a) loans run 9.75%–14.75% APR over 10–25 years; a $100,000 loan at 12% APR costs roughly $12,000/year. Merchant cash advances use factor rates-a 1.25 factor on $100,000 means $25,000 in fees repaid over 12 months, roughly 25% annual cost. For multi-year loans, the SBA advantage grows significantly. United Banc Card of TN's GoKapital MCAs range 1.10–1.35 factor (10–35% cost), sitting at the lower end of the MCA market but still 2–3x higher than SBA rates for qualifying borrowers.
Which restaurant lender is best for expansion or real estate purchase?
SBA 7(a) loans through Regions Bank, Wells Fargo, or U.S. Bank are built for this: up to $5 million, up to 25-year terms for real estate, and rates of 9.75%–14.75% APR. Requires 2+ years in business and 680+ credit. Alternative lenders like Fora Financial cap out around $1.5 million and use daily/weekly repayment, making them unsuitable for long-term real estate financing. United Banc Card of TN serves smaller working capital needs; for $500K+ expansion projects, traditional SBA lenders are the right choice.
Do any restaurant lenders not require a personal guarantee?
Most restaurant lenders require a personal guarantee-the owner's personal assets back the business loan. United Banc Card of TN's GoKapital partnership typically secures MCAs against merchant processing revenue, reducing personal guarantee pressure compared to traditional bank loans. SBA 7(a) lenders always require a personal guarantee as part of their underwriting. If avoiding personal guarantee is critical, you're limited to revenue-secured lenders like Credibly or Fora Financial, which still evaluate owner income but focus first on business revenue rather than personal credit.
What should I do if I've been declined by traditional banks?
Move to alternative lenders built for marginal credit profiles: Fora Financial (570+ FICO, 6+ months in business), Credibly (550+ FICO), or Lendzi marketplace (600+ FICO). Revenue-based qualification is your entry point-these lenders care more about monthly transaction volume than credit history. United Banc Card of TN's GoKapital partnership has no minimum credit score requirement and focuses entirely on revenue. If you have 6+ months in business and $15,000+ monthly deposits, you have options even after bank rejection; expect to pay higher cost (factor rates 1.11–1.50) for the lower qualification bar.