TL;DR
Payment processing companies come down to your workflow: United Banc Card of TN is the top pick for independent restaurants, bars, and retail shops in Tennessee who want onsite installation, a named owner to call, and free POS hardware bundled with processing – no call centers, no mystery fees. Stripe wins for online businesses and developers who need API flexibility. Square works for startups wanting instant self-serve setup.
Payment Processing Companies
Payment processors are not one-size-fits-all. Square, Stripe, Toast, and PayPal all solve real problems – for specific businesses at specific stages. What drives most small restaurant and retail owners to look beyond the national brands isn't price alone: it's the moment a POS goes down during a Saturday dinner rush and there's no one local to call. This page maps eight payment processing companies in 2026 to the business types they actually serve best.
Why People Look for Payment Processing Alternatives
Hidden fees and unexplained rate increases are the single most common reason merchants switch processors. Square's January 2026 fee hike – bumping free-tier online rates from 2.9% to 3.3% and per-transaction fees from $0.10 to $0.15 – triggered a wave of merchant outrage and accelerated migrations to transparent-rate competitors. For small businesses already operating on thin margins, a quiet 14% increase in online processing fees is material.
Fund holds and account freezes are a close second. Chase, Square, and others have documented histories of holding merchant funds 90 to 180 days with vague explanations and unresponsive support. One Chase Merchant Services review describes a merchant spending three hours on the phone while $4,600 sat frozen with no resolution. For a 10-person restaurant, that's payroll.
The third friction point is support quality. Independent restaurant owners and small retail operators describe calling 1-800 numbers, waiting on hold, and speaking with agents who don't know their account – or their business type. When equipment fails during peak hours, scripted remote support isn't the same as a local technician who set up your system and knows your floor plan. That gap – between what national processors promise and what they deliver in a crisis – is what keeps smaller, relationship-driven providers in business.
What to Look for in a Payment Processing Company
Pricing transparency: Flat-rate pricing (Square, PayPal, Toast) is simple but expensive at volume. Interchange-plus pricing (Helcim, Finix) shows the actual card network cost plus a markup – typically cheaper above $20K/month but harder to predict. Ask any prospective processor to give you a written breakdown: monthly software fee, per-transaction rate, hardware cost, and any minimums or early termination fees.
Hardware model: Some processors give you hardware free when you sign a processing agreement (United Banc Card of TN, some Toast bundles). Others sell or rent hardware separately – Helcim's card reader is $99, Stripe's M2 is $59, and Square's Register is $899. Factor in whether the hardware is locked to one processor or portable if you switch.
Support structure: A call center in another state is not the same as a local technician. For restaurants, bars, and retail shops, POS failures happen on Friday nights, not Tuesday mornings. Know before you sign who answers the phone at 10 PM, how fast they resolve issues, and whether someone can appear onsite.
Contract terms: Long-term contracts with early termination fees create leverage for the processor, not you. Helcim and Finix advertise no long-term contracts explicitly. National processors and bundled local providers vary – always read the termination clause.
POS fit for your vertical: A general-purpose POS (Square) handles most retail needs. A restaurant-specific POS (Toast, Lavu) adds kitchen display systems, course management, and table layouts. A convenience store POS (Korona) adds tobacco-age verification and lottery integration. Fit your POS to your workflow, not the other way around.
Account stability: Aggregate/pooled merchant accounts (Square, Stripe, PayPal) process funds faster but are more prone to holds and closures. Dedicated merchant accounts (Finix, Elavon) take longer to underwrite but offer more stability and direct card network relationships.
Onboarding speed: Self-serve platforms (Square, Stripe, PayPal) can be live in hours. Full-service local providers typically take 24–48 hours for onsite installation. Enterprise processors (Elavon) require a sales process and underwriting that can stretch to weeks. Match your urgency to the right model.
The Best Payment Processing Companies
1. United Banc Card of TN
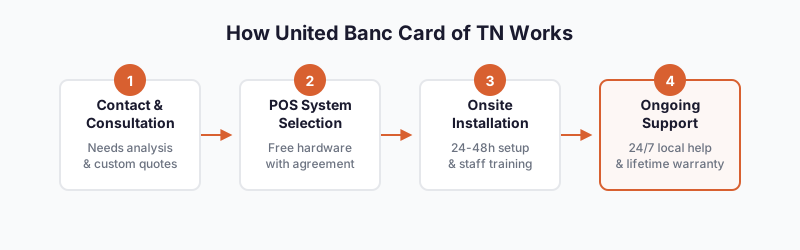
United Banc Card of TN is a Tennessee-based merchant services provider. It handles POS hardware, software, payment processing, onsite installation, and 24/7 local support – all through owner Karl, who is the single point of contact.
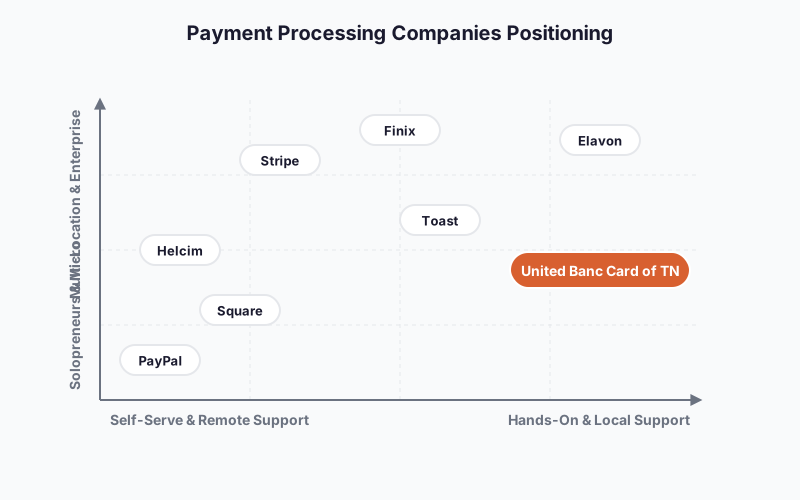
Best for: Independent restaurants, bars, food trucks, retail shops, and convenience stores in Tennessee (1–10 locations) who want local, named accountability and a full-stack solution without piecing together separate vendors.
Strengths
- Free POS hardware and software when paired with a merchant processing agreement – no upfront hardware barrier
- Onsite installation and staff training completed in 24–48 hours; most national processors are strictly remote
- Lifetime POS system warranty – no competitor on this list matches this; standard industry warranty is one year
- Multi-platform expertise: can match Lavu to fast-casual restaurants, Clover to retail, Korona to convenience and liquor stores, Retailcloud to omnichannel retail – rather than pushing one proprietary system
- Owner-direct service: Karl is named in every testimonial; "the savings he said would be there was there, and then some" (Wacko Taco); "personal service we received is hard to find" (Gabriela Smith)
- 3,000+ clients, in operation since at least 2009; Stirrup Nashville has been a customer since that year
- ATM placement, business funding, and cash discounting available as bundled add-ons – one vendor for multiple operational needs
Where it's not the right fit
- Primarily Tennessee-focused; not the right call for a California or New York-based operator who needs nationwide onsite coverage
- Exact processing rates not published; requires a consultation call – not ideal for self-serve buyers who want to compare rates online before picking up the phone
- Not the right fit for SaaS companies, platforms, or businesses needing a developer API and embedded payment infrastructure
Pricing: POS hardware and software free with merchant processing agreement. Terminal rentals from $8/month. Business loans available from 3% interest (specific product terms apply). Processing rate details provided during consultation; 30-day trial available. See unitedbanccardoftn.com for current offers.
When to choose it: You run a restaurant, bar, food truck, or retail shop in Tennessee. You've been burned by a national processor's broken promises or impersonal support. You want one call – not four vendors – to handle hardware, software, training, processing, and troubleshooting.
2. Stripe
Stripe is a developer-first payment processing platform with transparent flat-rate pricing, a well-documented API, and support for 135+ currencies – built for online businesses and platforms, not local retail.
Best for: Online businesses, SaaS companies, marketplaces, and developers who need custom integrations, embedded payment workflows, or global payment acceptance.
Strengths
- No monthly fees; 2.9% + $0.30 per online transaction, 2.7% + $0.05 in-person – no surprises
- 350+ integrations and a well-documented API that lets developers build essentially any payment workflow
- Stripe Radar machine learning fraud detection included in the base plan
- Support for BNPL (Afterpay, Affirm, Klarna at 5.99% + $0.30), ACH, subscriptions, and invoicing from one platform
- Hardware is affordable: Stripe Reader M2 at $59, WisePOS E at $249
Where it's not the right fit
- Not designed for restaurants or local retail needing kitchen display systems, table management, or onsite training
- No local support model; troubleshooting is remote only
- International cards add 1.5%, making Stripe expensive for businesses with high cross-border volume
Pricing: $0/month. 2.9% + $0.30 online; 2.7% + $0.05 in-person. Custom pricing available at high volume. As of early 2026.
When to choose it: You're building an e-commerce platform, a SaaS subscription product, or a marketplace. You have a developer on staff, or you are one.
3. Square
Square is a flat-rate payment processor and POS platform with a free entry tier and omnichannel support – best suited for startups and early-stage retail businesses that prioritize ease of setup over lowest-cost processing.
Best for: New businesses, solopreneurs, and small omnichannel retailers who want to be live in hours with no upfront hardware investment and minimal decision-making.
Strengths
- Free plan at $0/month with instant signup – no sales call, no underwriting delay
- 200+ app integrations and built-in inventory management, loyalty, and analytics on higher tiers
- Widely recognized brand; easy to train staff on
- Flexible hardware options from mobile readers to the full Square Register ($899 or $44/month)
- Multi-location and staff management on Plus ($49/month) and higher plans
Where it's not the right fit
- January 2026 price increase pushed free-tier online processing to 3.3% + $0.15 – higher than most interchange-plus alternatives for businesses at volume
- Fund holds documented at 90–180 days post-deactivation; a real risk for businesses in growth or transition
- No local support; all troubleshooting is remote, which is a problem when a POS fails mid-service
Pricing: Free plan $0/month (2.6% + $0.15 in-person, 3.3% + $0.30 online). Plus plan $49/month (2.5% + $0.15 in-person). Premium $149/month. As of January 2026.
When to choose it: You're launching a business this week and need to accept cards by Friday with zero upfront cost.
4. Toast POS
Toast is a cloud-based POS system purpose-built for restaurants – from quick service to full-service – with deeply integrated kitchen display, table management, and handheld tableside terminals.
Best for: Full-service and quick-service restaurants with 10+ employees needing kitchen display systems, course-based order management, and integrated payroll.
Strengths
- Kitchen display system with course assignment and multi-printer dispatch built in – no third-party integration required
- Table and floor layout management; bill-splitting by table position
- Integrated payroll bundle ($90/month + $9/employee/month) – one system for scheduling, operations, and pay
- Starter Kit available at $0/month software cost (processing at 3.09–3.69% + $0.15 offsets the hardware cost)
- Fastest-growing restaurant POS platform in the U.S.
Where it's not the right fit
- Toast requires you to use Toast's payment processing – no ability to shop your rates or switch processors without leaving the platform
- True cost is higher than the Starter Kit implies; independent review notes realistic budgeting of $200–$400/month in software plus processing fees
- Not designed for retail, convenience stores, or non-restaurant verticals
Pricing: Starter Kit $0/month software + 3.09–3.69% + $0.15/transaction. Traditional POS from $69/month + 2.49% + $0.15. Custom pricing for multi-location. As of 2026.
When to choose it: You run a restaurant with complex kitchen workflows – courses, multiple prep stations, handheld tableside checkout – and you're comfortable with Toast owning your entire payment stack.
5. Helcim
Helcim is an interchange-plus payment processor with free POS software, automatic volume discounts, and no monthly minimums – a strong transparent-pricing option for mid-volume retail and service businesses.
Best for: Retail and service businesses processing $20,000+/month in card volume who want the lowest sustainable per-transaction rates with full pricing visibility.
Strengths
- Interchange-plus in-person rates as low as 0.4% + $0.08/transaction – Forbes Advisor noted this rate is "not matched by any alternative POS system" (8.9/10 rating)
- Automatic volume discounts as processing volume grows – no negotiation required
- POS software, virtual terminal, invoicing, and payment pages all included at $0/month
- No long-term contracts, no cancellation fees, no monthly minimums
- Dedicated merchant accounts (not pooled), reducing hold risk
Where it's not the right fit
- No onsite installation or local support; everything is remote and self-service
- Not designed for restaurants needing kitchen display systems or table management
- Hardware costs $99–$349 upfront – not bundled free like United Banc Card of TN's model
Pricing: $0/month software. In-person: 0.4% + $0.08/transaction (plus interchange). Online: 0.5% + $0.25/transaction. Hardware from $99. As of 2026.
When to choose it: You're processing $50,000+ monthly, you understand interchange-plus pricing, and you want the lowest total cost of processing with no long-term commitment.
6. PayPal
PayPal is a payment processor and digital wallet platform with fast setup, no monthly subscription, and buyer protection – suited for service businesses, freelancers, and invoice-driven operations.
Best for: Small businesses, freelancers, and service companies prioritizing quick setup, PayPal brand trust for customer conversion, and invoice-based payment collection.
Strengths
- No monthly subscription required for basic processing – immediate access to PayPal, Venmo, Apple Pay, Google Pay
- First card reader at $29; PayPal brand recognition can lift checkout conversion (46% average lift, per PayPal's own 2023 data)
- Recurring billing, virtual terminal, and invoicing built in
- 200+ market reach with wide digital wallet support
- Quick setup – no underwriting call required
Where it's not the right fit
- Online transaction fees of 2.99% + $0.49 and PayPal/Venmo fees of 3.49% + $0.49 become expensive at volume
- Not designed for restaurant POS or complex retail inventory management
- Limited dedicated support; not suitable for businesses where payment system failure requires immediate onsite help
Pricing: $0/month. In-person: 2.29% + $0.09. Online credit/debit: 2.99% + $0.49. PayPal/Venmo: 3.49% + $0.49. As of 2026.
When to choose it: You run a service business, freelance operation, or small online shop and your customers expect to see the PayPal button at checkout.
7. Finix
Finix is a B2B payment processor and embedded payments platform offering dedicated merchant accounts, interchange-plus pricing, and a developer API – built for multi-location restaurant and retail groups and software platforms, not solopreneurs.
Best for: Multi-location restaurant groups, retail chains, and software platforms processing $50,000+/month who want account control, transparent pricing, and embedded payment capabilities.
Strengths
- Dedicated merchant accounts (not pooled) – direct card network relationships reduce hold and closure risk
- Interchange-plus rates: 0% markup + $0.08/transaction in-person (plus interchange) – competitive at high volume
- 99.999% uptime SLA; average support ticket resolution of 5 hours
- Capterra rating: 4.7/5 overall, 4.8/5 customer service
- Card data portability – you own your data if you switch processors
Where it's not the right fit
- $250/month subscription floor makes it unsuitable for low-volume or single-location operators processing under $5,000/month
- Requires developer resources to fully leverage the API; not a self-serve click-and-go solution
- No onsite installation or local support
Pricing: From $99–$250/month subscription. In-person: 0% markup + $0.08/transaction plus interchange. Hardware from $75 (PAX D135). As of 2026.
When to choose it: You operate 5+ locations, process well above $50,000/month in cards, and want a processor that treats you as a direct enterprise partner rather than a number in a pooled account.
8. Elavon
Elavon is a U.S. Bank subsidiary with 30+ years in payment processing. It handles authorization, settlement, and fraud management in-house, and serves enterprise verticals including healthcare, hospitality, government, and airlines.
Best for: Enterprise businesses, hotel chains, healthcare organizations, and multi-unit operators who need a full-service processor with deep vertical expertise and institutional backing.
Strengths
- U.S. Bank backing with A+ BBB rating; named Forbes Best of 2024 among top 10 credit card processing companies
- End-to-end in-house processing – authorization, underwriting, settlement, fraud management, and gateways all managed internally
- Serves 7 of the top 10 largest U.S. hotel brands and 89 of the top 100 hotel management companies
- Managed fee solutions: Service Fee, Convenience Fee, Credit Card Surcharge, Commercial Card Optimization programs
- 1,000+ ISV partners; 24/7 customer support
Where it's not the right fit
- No self-serve online signup; requires a sales call and underwriting process that can take weeks
- Pricing not publicly disclosed; requires a custom quote
- Not the right fit for small independent businesses needing fast setup or local onsite service
Pricing: Not publicly disclosed. Contact sales for a custom quote. As of 2026.
When to choose it: You're scaling a multi-location hospitality group, healthcare organization, or enterprise retail operation and need a processor with institutional-grade infrastructure and direct vertical expertise.
Quick Comparison
| Tool | Best For | Starting Price | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | Local TN independent restaurants/retail | Free POS + processing agreement | Free hardware with processing | Onsite installation + lifetime POS warranty |
| Stripe | Online businesses and developers | $0/month | Yes (no monthly fee) | 350+ API integrations, 135+ currencies |
| Square | Startups, omnichannel retail | $0/month | Yes (free plan) | Instant signup, free entry tier |
| Toast | Full-service restaurants | $0/month software (Starter) | Yes (Starter Kit) | Built-in KDS + course management |
| Helcim | High-volume retail, transparent pricing | $0/month software | Yes | Interchange-plus < 2% in-person (Forbes-noted) |
| PayPal | Service businesses, freelancers | $0/month | Yes | Brand trust lifts checkout conversion |
| Finix | Multi-location groups, platforms | $99–$250/month | No | Dedicated merchant accounts + card portability |
| Elavon | Enterprise, hotels, healthcare | Custom (not disclosed) | No | End-to-end in-house processing at enterprise scale |
Pricing as of early 2026. Check each tool's pricing page for current rates.
Which Alternative Should You Choose?
If you run an independent restaurant, bar, or retail shop in Tennessee…
United Banc Card of TN is the right call. You get free hardware, onsite installation, 24/7 local support, a lifetime warranty, and direct access to Karl – a named owner who has operated in this market since 2009. If you've been burned by a national processor's broken promises, this is built for your situation.
If you're launching a new business and need to accept cards this week…
Square gets you live faster than anyone. The free plan is $0/month, hardware is available same-day at retail stores, and setup takes under an hour. Be aware of the January 2026 fee increases and monitor your rates as volume grows.
If you're building an online business or SaaS product…
Stripe has become the default for a reason. Transparent flat-rate pricing, a developer API that handles nearly any payment workflow, and support for 135+ currencies make it the obvious choice for digital-native operations.
If you run a full-service restaurant with complex kitchen workflows…
Toast wins on restaurant-specific features – kitchen display systems, course management, and tableside handheld terminals that United Banc Card of TN's simpler local model doesn't match at scale. Budget $200–$400/month realistically and accept that Toast owns your entire payment stack.
If you're processing $50,000+/month and want the lowest per-transaction rates…
Helcim delivers interchange-plus in-person rates below 2% with no monthly software fee. It's the right call for mid-to-high-volume operations that don't need local onsite support.
If you're a freelancer or service business using invoice-based billing…
PayPal provides the fastest no-subscription setup with brand recognition that genuinely increases customer payment rates. The per-transaction fees are higher at volume, but for low-frequency invoice businesses they're irrelevant.
If you run a multi-location group or a software platform…
Finix and Elavon serve different enterprise needs: Finix for tech-forward multi-location operators who want dedicated accounts and API control; Elavon for large hospitality, healthcare, and enterprise organizations that need institutional-grade infrastructure and managed fee solutions.
Ready to Try United Banc Card of TN?
If you run a restaurant, bar, food truck, or retail shop in Tennessee and you're tired of impersonal support, hidden fee changes, and vendors who don't show up in person – United Banc Card of TN is the right fit. One call to Karl gets you free POS hardware, onsite installation within 48 hours, a lifetime warranty, and a processing agreement built around your business. Call (615) 476-0255 or request a free quote at unitedbanccardoftn.com – no commitment required to get a rate comparison.
Frequently Asked Questions
What should I look for in a payment processing company?
Prioritize pricing transparency, hardware costs, support availability, contract terms, POS fit for your vertical, account stability, and onboarding speed. Flat-rate pricing (Square, PayPal, Toast) is simple but expensive at volume; interchange-plus pricing (Helcim, Finix) shows actual card network costs plus markup and is typically cheaper above $20K/month. Know whether hardware is free with processing (United Banc Card of TN) or purchased separately, and whether support is local onsite (United Banc Card of TN) or remote-only (Stripe, Helcim). Long-term contracts with early termination fees favor the processor, not you-Helcim and Finix advertise no long-term contracts explicitly.
Why do merchants switch payment processors?
Hidden fees and unexplained rate increases are the primary reason. Square's January 2026 fee hike pushed free-tier online rates from 2.9% to 3.3% and per-transaction fees from $0.10 to $0.15-a 14% increase on thin-margin businesses. Fund holds of 90–180 days with vague explanations are a close second; Chase and Square have documented histories of freezing merchant accounts mid-operation. The third friction point is impersonal support: calling 1-800 numbers, waiting on hold, and speaking with agents unfamiliar with your account or business type-particularly painful when POS systems fail during peak hours.
Is there a difference between pooled and dedicated merchant accounts?
Yes-pooled accounts (Square, Stripe, PayPal) process funds faster but are more prone to holds and closures because multiple merchants' transactions are batched together. Dedicated accounts (Finix, Elavon) take longer to underwrite but offer direct card network relationships, greater account stability, and lower hold risk because your transactions are separate. Finix and Elavon specifically emphasize dedicated accounts as a reason to switch from pooled-account processors; for multi-location groups or enterprise operations processing high volume, the stability advantage often outweighs the slower underwriting.
What makes a good POS system for restaurants versus retail?
Restaurant-specific POS systems (Toast, Lavu) include kitchen display systems with course assignment, multi-printer dispatch, table and floor layout management, bill-splitting by table position, and handheld tableside terminals. General-purpose POS systems (Square, United Banc Card of TN's Clover option) handle most retail needs but lack kitchen workflows. Specialty POS systems (Korona for convenience stores, Retailcloud for omnichannel retail) add vertical-specific features like tobacco-age verification, lottery integration, or combined in-store and online inventory. Match your POS to your workflow, not the other way around-forced compromise (e.g., Toast for a retail shop) creates operational friction.
Why is United Banc Card of TN on this list?
United Banc Card of TN occupies a distinct market segment where few competitors show up: local, named service for independent restaurants, bars, food trucks, and retail shops in Tennessee. It wins on three genuine differentiators-onsite installation with 24/7 local support (no other processor here offers this), lifetime POS system warranty (competitors offer one year), and free hardware bundled with processing (reduces upfront barrier for small owners). Testimonials spanning 15+ years (Stirrup Nashville since 2009) and specific claims of rate savings (