TL;DR
Merchant cash advance direct lenders come down to your situation and what you need beyond the capital itself. United Banc Card of TN is the top pick for independent Tennessee restaurants, bars, and retail owners who want bundled POS, processing, and funding from one named local contact – not a call center. Credibly wins for prime borrowers seeking the lowest factor rates (starting at 1.11×), and Reliant Funding is the strongest option for borrowers with no established credit history.
Merchant Cash Advance Direct Lenders
Merchant cash advance direct lenders have made business capital genuinely accessible. The 70–80% approval rates versus under 14% at large banks isn't a marketing claim, it's a documented market shift. But with at least 700 MCA providers operating nationwide, picking the wrong one means overpaying by tens of thousands of dollars in factor rate differences, signing opaque terms, or funding without the operational infrastructure your business actually needs. This page breaks down six leading providers by use case so you can match the right lender to your situation.
Why People Look for Merchant Cash Advance Direct Lenders
The biggest frustration merchants bring to this search is opacity around what they're actually paying. A $50,000 advance at a 1.2× factor rate sounds like 20% interest, but annualized over a six-month repayment period, that's an effective APR closer to 40–80%. Most MCA marketing leads with factor rates precisely because the math sounds better than it is. Reddit threads on small-business financing consistently flag this as the primary pain: "It's 50% interest only" is a verbatim complaint from one small-business owner after signing what was marketed as a straightforward advance.
The second friction point is broker opacity. Many lenders presenting as "direct funders" are actually brokers shopping your application to 50+ underlying funders. When you're not certain who ultimately holds your advance, negotiating or disputing terms becomes much harder. Reliant Funding, for example, operates a network of 50+ MCA providers – not a single in-house funder – despite its direct-lender positioning.
Third is stacking risk. Businesses that take two or more concurrent MCAs default at 3–5× higher rates than single-advance borrowers. Yet many lenders approve second and third stacks without counseling borrowers on the compounding daily ACH deductions that follow. Knowing the fit and limits of each provider before applying is how you avoid this.
What to Look for in a Merchant Cash Advance Lender
Factor rate range. This single number determines total repayment cost. A difference between 1.15× and 1.35× on a $100,000 advance is $20,000 in extra repayment. Ask for the specific range for your risk profile, not the advertised minimum floor, before signing anything.
Minimum revenue and credit requirements. Lenders set different floors. Credibly requires a 500 credit score and $15,000/month revenue; Fora Financial requires 570 and $20,000/month. Knowing the floor before you apply saves weeks of wasted application time if your profile doesn't qualify.
Speed vs. total cost. OnDeck can fund $1,000–$10,000 within 30 minutes. That speed premium comes with APRs of 39–99%. If you need capital in four hours, that cost may be justified. If you have 24–48 hours, Credibly at a 1.11× factor rate will cost you considerably less on the same advance amount.
Full fee structure, not just the headline rate. Origination fees ($50–$3,000+), UCC filing fees ($295 at Credibly), and administrative charges ($50/month on some products) add materially to effective cost. Require a complete fee schedule before signing.
Bundled vs. capital-only. National MCA lenders deliver capital and nothing else. If you need POS hardware, processing infrastructure, or onsite operational support alongside funding, a capital-only advance means sourcing those separately, which adds vendors, contracts, and support queues to your workload.
Accountability and support. When something goes wrong, a payment dispute or a daily ACH deduction that strains your cash flow, do you have a named contact or a ticket number? The difference between a local provider you can call directly and a national lender's support queue is real when you're in a cash crisis.
Geographic service area. Credibly, Fora, and OnDeck serve all 50 states. United Banc Card of TN primarily serves Tennessee merchants. If you're outside Tennessee, national lenders are the only viable path for the bundled model.
The Best Merchant Cash Advance Direct Lenders
1. United Banc Card of TN
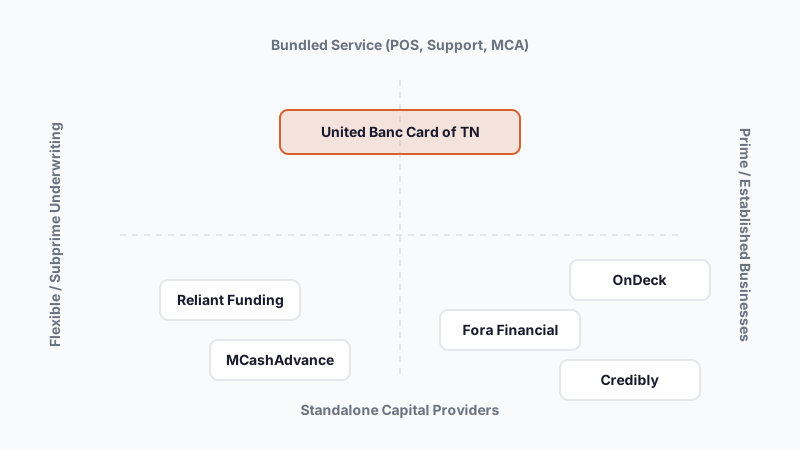
United Banc Card of TN is a Tennessee-based merchant services provider that bundles merchant cash advances (via GoKapital partnership) with POS systems, credit card processing, onsite installation, and 24/7 local support. One named owner, Karl, manages all of it.
Best for: Independent Tennessee restaurants, bars, food trucks, and retail stores under 10 employees who want one local provider for POS hardware, card processing, and business funding.
Strengths
- Bundles MCA with free POS hardware (when paired with a processing agreement), onsite installation, staff training, and a lifetime POS warranty. No national MCA lender offers any of this
- Karl personally handles consultations, rate negotiations, and onsite support. Customer testimonials spanning 15+ years include "personal service hard to find" and "the savings he said would be there was there, and then some"
- Minimum $20,000/month in card processing revenue qualifies for MCA; approved for up to 150% of average monthly revenue with no prepayment penalties
- 24/7 local technical support. When your POS fails on a Saturday dinner rush, you reach a local technician, not a national call center
- 10+ years in the Tennessee market; 3,000+ clients served
Where it's not the right fit
- Primarily serves named Tennessee cities (Nashville, Murfreesboro, Franklin, Brentwood, and surrounding areas); not designed for businesses outside Tennessee
- Pricing is not publicly disclosed. You'll need a direct consultation to get a quote, which adds friction for borrowers who prefer to compare rates online before talking to anyone
- The MCA product is paired with a merchant services relationship; pure capital-seekers who already have a POS setup may prefer a standalone MCA lender
Pricing: MCA pricing via GoKapital partnership – terms disclosed during consultation. Terminal rentals from $8/month; POS hardware free with processing agreement. As of 2025.
When to choose it: You're a Tennessee-based independent restaurant, bar, or retailer who wants one contact for POS hardware, card processing, and business funding – and you value the accountability of a named local provider over the convenience of online rate comparisons.
2. Credibly
Credibly is a direct MCA lender and small-business financing marketplace offering advances from $5,000 to $600,000, with factor rates starting at 1.11×. That's the lowest published starting rate among the lenders in this comparison.
Best for: Established businesses with $15,000+ monthly revenue and 500+ credit scores who want the most competitive factor rates from a direct lender with published pricing.
Strengths
- Factor rates starting at 1.11×: a 1.11× rate on a $50,000 advance means repaying $55,500 total, the most competitive starting rate in this comparison
- Approvals in as little as 4 hours; funding typically within 24 hours of contract acceptance
- No origination fees on the core MCA product; the $295 UCC filing fee is the main upfront cost
- Accepts credit scores as low as 500 (soft pull only)
- 4.9/5 stars on LendingTree with 20 verified reviews; reviewers consistently mention fast funding and clear terms
Where it's not the right fit
- Marketplace structure can slow approvals for applicants with monthly revenue under $25,000, or those in higher-risk industries like restaurants and construction
- Does not offer POS systems, processing infrastructure, or any operational support – capital only
- $15,000/month revenue minimum excludes very early-stage or very low-volume businesses
Pricing: Factor rates from 1.11×; no origination fee on MCA; $295 UCC filing fee; 2.5% origination plus $50/month admin fee on some partner products. As of 2025.
When to choose it: You have $15,000+ monthly revenue, a 500+ credit score, and need capital within 24 hours at the most competitive available factor rate – and you don't need integrated POS or local operational support.
3. Fora Financial
Fora Financial is a direct MCA lender specializing in revenue advances from $5,000 to $1.5 million, with flexible repayment that adjusts when revenue dips and early payoff discounts that are rare in this industry.
Best for: Businesses with seasonal or variable revenue that need repayment flexibility, or owners who want a real early-payoff incentive baked into their advance agreement.
Strengths
- Revenue-based repayment adjusts daily ACH deductions downward when your sales slow. Lower revenue means lower daily payments, which protects cash flow during off-seasons
- Early payoff discounts available – rare in an industry where paying off early typically saves nothing
- Advances up to $1.5 million – the largest ceiling among the providers listed here
- 4.5/5 Trustpilot rating; reviewers call out the repayment flexibility specifically
- Structured revenue advance option gives you a fixed repayment schedule rather than purely variable daily deductions, which makes cash flow easier to plan
Where it's not the right fit
- 3% origination fee adds meaningfully to effective cost; on a $100,000 advance, that is $3,000 upfront before any factor-rate repayment begins
- Minimum 570 credit score requirement is higher than Credibly (500) or MCashAdvance
- $240,000 annual revenue minimum ($20,000/month) required; not accessible to lower-volume merchants
Pricing: Factor rates 1.13 to 1.50×; 3% origination fee; repayment terms up to 18 months for revenue advances, 24 months for structured loans. As of 2025.
When to choose it: Your business has seasonal revenue swings and you need an advance that flexes with your cash flow – or you want the option to pay off early and actually realize a cost reduction for doing so.
4. OnDeck
OnDeck is a diversified small-business lender with an A+ BBB rating since 2008. It offers term loans, lines of credit, and MCA-adjacent products to businesses that want multi-product financing from a single lender, and it has the most extensive third-party review record of any provider in this comparison.
Best for: Established businesses with strong cash flow that want access to multiple loan products, or first-time MCA borrowers who prioritize third-party credibility and long track records over lowest cost.
Strengths
- 4.7/5 stars on Trustpilot from 6,000+ reviews and A+ BBB accreditation since 2008, the deepest independent review record in this list
- Instant funding possible for $1,000–$10,000 within 30 minutes for eligible borrowers, which is the fastest small-ticket option in this comparison
- Term loans ($6,000–$200,000), lines of credit, and MCA-adjacent products available from a single lender relationship
- Per a Federal Reserve survey cited on OnDeck's site, 10% of small businesses seeking financing in 2022 pursued OnDeck. That volume means their underwriting criteria are well-established and consistent
Where it's not the right fit
- Not a specialist MCA lender; factor rate structure isn't prominently disclosed; term loan APRs of 39–99% can exceed MCA equivalents for very short repayment terms
- Prime borrowers will get lower effective costs from Credibly's 1.11× starting factor rate than from OnDeck's 39% floor APR
- Does not offer POS systems, processing agreements, or any operational infrastructure
Pricing: Term loans at estimated APR 39–99%; advances $6,000–$200,000; instant funding for small amounts ($1K–$10K). As of 2025.
When to choose it: You want the most widely reviewed lender in this market, need funds within 30 minutes, or want access to term loans and lines of credit beyond a one-time advance – and you're willing to pay a premium for that breadth.
5. Reliant Funding
Reliant Funding is a marketplace-style MCA provider built on a network of 50+ underlying funders. It specifically targets businesses with poor or no credit history that have been turned down by other lenders.
Best for: Businesses with credit scores below 550, no established credit history, or those that have already been declined by Credibly or Fora Financial.
Strengths
- No stated minimum credit score – the most accessible underwriting standard in this comparison
- Factor rates starting at 1.10×; $495 flat origination fee, lower than most comparable providers
- Funding within one business day; approval within hours of application
- Network of 50+ underlying funders raises the odds of matching any applicant to an available capital source
Where it's not the right fit
- 2.8/5 stars on TrustPilot; no longer BBB-accredited. That's the weakest customer satisfaction profile among the providers listed here
- Broker model (not a direct in-house funder) can slow deal closure; applicants may not know which entity ultimately holds their advance
- Factor rates up to 1.50× apply to subprime profiles; the 1.10× floor is reserved for prime borrowers
Pricing: Factor rates 1.10 to 1.50×; $495 origination fee; funding $2,000 to $2,000,000; repayment 2 to 24 months. As of 2025.
When to choose it: Your credit score is below 550, you've been declined by other lenders, and you need capital within one business day – speed and access matter more than rate optimization in your situation.
6. MCashAdvance
MCashAdvance is an MCA provider with a published rate structure, soft-pull-only underwriting, and explicit acceptance of subprime borrowers on a case-by-case basis. It has one of the lowest revenue thresholds in the market.
Best for: Very low-revenue businesses ($7,500+ monthly card sales) or borderline-credit borrowers who want to see published rates before committing, without a hard credit inquiry.
Strengths
- Soft pull only (Lexis-Nexis background check, not a traditional credit pull) – does not impact your credit score at any point in the application
- Factor rates 1.1 to 1.5× with holdback of 10–25%; published rate structure you can review before applying
- Accepts subprime borrowers with credit below 500 on a case-by-case basis
- $7,500/month in card sales is the lowest revenue minimum among the providers in this list
- Funds in 1–2 business days after contract acceptance
Where it's not the right fit
- Minimal independent third-party review presence; primarily self-reported testimonials – harder to verify claims than with Credibly or OnDeck
- Factor rates at the higher end of the market range for subprime borrowers; prime borrowers will get better rates from Credibly or Fora
- Limited geographic specificity on service areas; unclear how consistently national coverage is provided
Pricing: Factor rates 1.1 to 1.5×; holdback rate 10–25%; advances $5,000 to $900,000; repayment 3–18 months. As of 2025.
When to choose it: Your monthly card sales are $7,500–$15,000, your credit score is below 550, and you want a soft-pull-only application with a published rate structure you can review before you talk to anyone.
Quick Comparison
| Tool | Best For | Starting Price | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | TN restaurants needing bundled POS + MCA + support | Consultation required | Free POS hardware w/ processing | Full-stack local service: POS, MCA, ATM, onsite install |
| Credibly | Prime borrowers needing lowest factor rates | 1.11× factor rate | No | No origination fee + 4-hour approval |
| Fora Financial | Seasonal businesses, early payoff option | 1.13× factor rate | No | Revenue-adjusted repayment + early payoff discounts |
| OnDeck | Multi-product financing, instant small-amount funding | 39% APR | No | 30-min instant funding; 6,000+ Trustpilot reviews, A+ BBB |
| Reliant Funding | No-credit-check borrowers, same-day access | 1.10× factor rate | No | No stated minimum credit score |
| MCashAdvance | Low-revenue businesses, soft-pull-only | 1.10× factor rate | No | $7,500/mo revenue floor + no hard credit check |
Pricing as of 2025. Check each provider's current terms directly – MCA factor rates change with market conditions and borrower risk profiles.
Which Alternative Should You Choose?
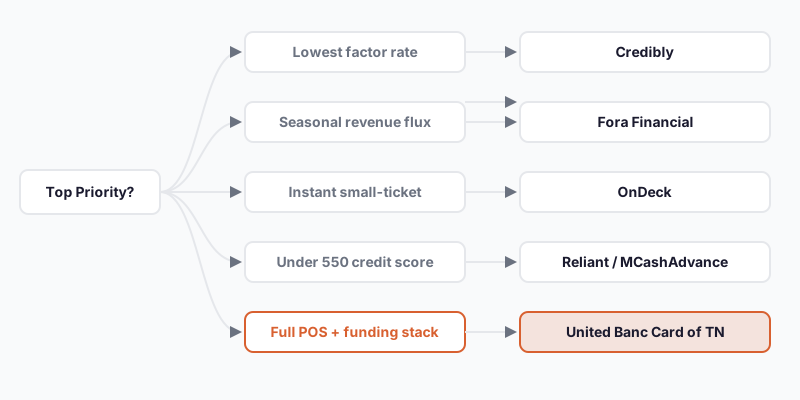
If you need the lowest factor rate and have strong revenue…
Credibly is your best option. With factor rates starting at 1.11× and no origination fee on the core MCA product, a prime borrower ($15,000+ monthly revenue, 500+ credit score) gets the most competitive total repayment cost available. Four-hour approvals mean you are not trading cost for speed.
If your revenue fluctuates seasonally…
Fora Financial is the right fit. Its revenue-based repayment structure reduces daily ACH deductions when your sales dip. That matters a lot for restaurants, retailers, and event-based businesses that see wide swings by quarter or season.
If you need funding within 30 minutes…
OnDeck offers instant funding for $1,000–$10,000 within 30 minutes for eligible borrowers. Its 6,000+ Trustpilot reviews and A+ BBB accreditation since 2008 also make it the lowest-risk choice for first-time MCA borrowers who want independent verification before committing.
If your credit score is below 550 or you've been turned down elsewhere…
Reliant Funding or MCashAdvance are the most accessible paths. Reliant has no stated credit score minimum and funds within one business day. MCashAdvance does a soft pull only and accepts subprime borrowers on a case-by-case basis with a $7,500/month card sales floor, the lowest entry point in this list.
If you're a Tennessee restaurant, bar, or retailer who needs POS, processing, and funding from one provider…
United Banc Card of TN is built for exactly this situation. Instead of managing separate vendor relationships for your POS system, merchant processor, and capital lender, you get the full stack from a single Tennessee-based owner who named customers have worked with for 15+ years. The MCA comes with free POS hardware, onsite installation, staff training, and 24/7 local support. No national MCA provider on this list offers that operational infrastructure at any price.
If your monthly card sales are under $15,000 and you want to see rates before applying…
MCashAdvance has the lowest published revenue floor in this comparison at $7,500/month in card sales, a published rate structure you can check before applying, and no hard credit pull during the process. It's a workable path for early-stage or low-volume merchants who don't meet Credibly's or Fora's minimums.
Ready to Try United Banc Card of TN?
If you're a Tennessee restaurant, bar, food truck, or retail owner who wants one contact for POS hardware, card processing, and business funding – not three separate vendors – United Banc Card of TN is the only provider here that handles the entire stack locally. Call Karl directly at (615) 476-0255 or request a free quote online. Most setups complete within 24–48 hours, and customers have been renewing that relationship since 2009.
Frequently Asked Questions
What should I look for in a merchant cash advance lender?
Factor rate range is the single most important criterion-a difference between 1.15× and 1.35× on a $100,000 advance equals $20,000 in extra repayment cost. Beyond rate, verify minimum revenue and credit requirements upfront, understand the complete fee structure (origination, UCC filing, administrative charges), and assess whether you need bundled services like POS hardware and onsite support or capital only. Speed, accountability (named contact vs. ticket system), and geographic service area matter significantly depending on your timeline and location.
What is the difference between factor rate and APR in merchant cash advances?
Factor rate multiplies your advance amount to determine total repayment; a 1.2× factor rate on $50,000 means repaying $60,000 total. When annualized over typical 6-month repayment periods, that same 1.2× factor rate translates to an effective APR of 40–80%, which is why lenders lead with factor rates in marketing-the number sounds more favorable. Always request the annualized equivalent to compare true cost across lenders and repayment timeframes.
Who are the best merchant cash advance direct lenders for fast funding?
OnDeck offers the fastest small-ticket funding, delivering $1,000–$10,000 within 30 minutes for eligible borrowers, though APRs of 39–99% reflect the speed premium. Credibly and Reliant Funding both approve and fund within 24 hours with lower rates starting at 1.11× and 1.10× respectively. If you need funding within one business day and value reputation, OnDeck's 4.7/5 Trustpilot rating and A+ BBB accreditation since 2008 make it the lowest-risk choice among fast options.
What is the minimum revenue required to qualify for a merchant cash advance?
Minimum revenue requirements vary by lender. Credibly and Fora require $15,000–$20,000 per month; United Banc Card of TN requires $20,000 per month; Reliant Funding and OnDeck have published minimums in the $15,000 range; MCashAdvance has the lowest floor at $7,500 per month in card sales. Knowing the floor before applying saves time if your monthly revenue falls below a lender's threshold, which is especially important for early-stage or seasonal businesses.
Do merchant cash advance lenders do hard credit pulls?
Most MCA lenders including Credibly, Fora, and Reliant Funding perform soft credit pulls that don't impact your credit score during underwriting. MCashAdvance explicitly uses soft pulls only via Lexis-Nexis background checks rather than traditional credit inquiries. This means you can apply to multiple lenders and compare offers without cumulative damage to your credit score from multiple hard inquiries.
What makes United Banc Card of TN different from national merchant cash advance lenders?
United Banc Card of TN bundles merchant cash advances with free POS hardware, onsite installation, staff training, lifetime warranty, and 24/7 local support from a named owner-Karl-who personally handles every relationship. National MCA lenders like Credibly and Fora deliver capital only; they don't provide operational infrastructure or local accountability. For Tennessee independent restaurants and retailers, this full-stack bundled model means one vendor relationship instead of managing separate POS, processing, and lending contacts, which is a genuine operational advantage that national capital-only lenders cannot replicate at any price.
Is United Banc Card of TN available outside Tennessee?
United Banc Card of TN primarily serves named Tennessee cities including Nashville, Murfreesboro, Franklin, Brentwood, Clarksville, and surrounding areas. While some pages claim nationwide merchant services capability, the MCA lending and bundled POS service is explicitly Tennessee-focused based on public materials and service footprint. If you're outside Tennessee, Credibly, Fora, OnDeck, or Reliant Funding are the viable options, as they serve all 50 states.
Which merchant cash advance lender is best for seasonal businesses?
Fora Financial is purpose-built for seasonal revenue swings; its revenue-adjusted repayment structure lowers daily ACH deductions automatically when your sales dip, protecting cash flow during slower quarters. This flexibility is especially valuable for restaurants, retail, and event-based businesses that see wide quarterly or seasonal swings. Fora also offers early payoff discounts, which are rare in the MCA industry and let you reduce total repayment cost if cash flow permits faster repayment.
What are the typical factor rates across merchant cash advance lenders?
Factor rates in this market range from 1.10× (Reliant Funding, MCashAdvance floor) to 1.50×+ for subprime borrowers. Credibly's 1.11× is the lowest published starting rate for prime borrowers; Fora starts at 1.13×. The specific rate you receive depends on monthly revenue, credit score, industry, and credit processing history-prime borrowers ($25,000+ monthly revenue, 600+ credit score) qualify for the lower end; subprime borrowers below 550 credit score typically see rates between 1.30–1.50×.
Should I apply to multiple merchant cash advance lenders at once?
Yes, applying to multiple lenders within a short window (same week) is standard practice and all soft-pull-only lenders show minimal cumulative impact to your credit score. Credibly, Fora, OnDeck, Reliant, and MCashAdvance all use soft pulls or don't report to credit bureaus, so you can gather competing offers for comparison without penalty. However, taking two or more concurrent advances compounds daily ACH deductions and default risk increases 3–5×, so compare offers and choose one before accepting capital.
What fees beyond the factor rate should I expect in a merchant cash advance?
Origination fees range from $0 (Credibly) to $3,000+ (Fora at 3%), UCC filing fees average $295 (Credibly), and some lenders charge monthly administrative fees of $50. MCashAdvance charges a $495 flat origination fee; Reliant charges $495 as well. Always request a complete written fee schedule before signing-the factor rate alone doesn't reflect true cost when origination and administrative fees can add 2–5% more to your effective repayment burden.
Is Credibly the best merchant cash advance lender overall?
Credibly is the best for prime borrowers ($15,000+ monthly revenue, 500+ credit score) seeking the lowest factor rate; its 1.11× starting rate and zero origination fee on core MCA products are the most competitive in this market. However, it's not universally the best-Fora Financial wins for seasonal businesses needing payment flexibility; OnDeck wins for instant $1K–$10K funding; Reliant wins for borrowers below 550 credit score; United Banc Card of TN wins for Tennessee merchants needing bundled POS plus funding. The best lender depends entirely on your specific revenue, credit profile, location, and operational needs.
How quickly can I get funded from a merchant cash advance lender?
Funding speed varies significantly. OnDeck funds $1,000–$10,000 within 30 minutes for eligible borrowers; Credibly typically funds within 24 hours of contract acceptance; Reliant Funding funds within one business day; Fora and MCashAdvance fund within 1–2 business days; United Banc Card of TN requires 24–48 hours including onsite POS installation. If same-day funding is critical, OnDeck is the only option with a 30-minute guarantee; if you have 24 hours, Credibly at better rates becomes feasible.
Can I get a merchant cash advance with no credit check?
No true 'no credit check' MCA exists, but several lenders use soft pulls that don't impact your credit score and accept subprime borrowers. MCashAdvance uses soft-pull-only underwriting via Lexis-Nexis; Reliant Funding has no stated minimum credit score and performs a soft pull; both explicitly serve borrowers below 550 credit. The key distinction is soft-pull (doesn't harm your score) versus hard-pull (does harm your score)-even soft-pull lenders assess your creditworthiness, just without reporting to bureaus.
What is the best merchant cash advance option for a Tennessee independent restaurant?
United Banc Card of TN is purpose-built for this exact situation. It bundles POS hardware (Lavu, Clover, Korona, Retailcloud options), merchant processing, MCA funding, onsite installation, staff training, and 24/7 local support from named owner Karl into a single vendor relationship. Testimonials from Tennessee restaurant customers spanning 15+ years emphasize relationship stability and integrated service that national MCA lenders cannot replicate. If price is your only criterion and you don't need POS or local support, Credibly's 1.11× factor rate is cheaper-but for bundled operational value, United Banc Card of TN has no competitor in the Tennessee market.