
TL;DR
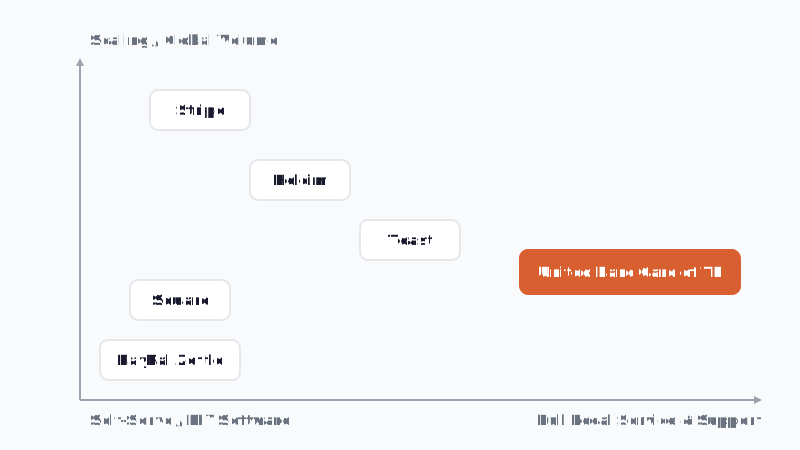
Credit card processors online come down to your workflow: United Banc Card of TN is the top pick for Tennessee independent restaurants, retailers, and service businesses who want a single local contact handling hardware, software, processing, and support – with a lifetime POS warranty and free equipment bundled in. Helcim wins for high-volume businesses processing $50K+/month who need transparent interchange-plus pricing that scales down automatically. Square works for very small, no-commitment early-stage businesses that need the simplest possible starting point.
Credit Card Processors Online
Credit card processors online span a wide range – from developer-first APIs like Stripe to local full-stack partners like United Banc Card of TN – and the right one depends entirely on whether your business needs automation or accountability. Square built its reputation on simplicity, but a January 2026 online rate hike (2.9% → 3.3% on the Free plan) has pushed many merchants to re-evaluate. This page compares the six strongest options across pricing, support model, and real-world fit so you can make the decision once and get on with running your business.
Why Merchants Struggle to Choose Credit Card Processors Online
The pricing on processor websites rarely matches what you actually pay. Square lists 2.6% + $0.15 for in-person and 3.3% + $0.30 online – but add monthly software fees, chargeback costs, and rapid deposit surcharges and the effective rate climbs fast. Merchants on Reddit's /r/smallbusiness have documented this gap for years: processors publish headline rates, not all-in rates.
Support is the second major frustration. National processors (Square, Stripe, PayPal) are aggregator models – your account is automated, and when something goes wrong during a Friday dinner rush, you're calling a queue. Independent restaurant owners in particular describe this as a breaking point: "Credit Card Processing can be very confusing, but Karl always took care of us and made it easy. The personal service we received is hard to find," as Gabriela Smith put it in a testimonial for United Banc Card of TN.
The third problem is hardware fragmentation. Signing up for Stripe doesn't get you a POS system – you still need to source terminals, configure software, and train staff. For small business owners who aren't technical, cobbling together three vendors to accept payments creates the exact operational headache they were trying to solve. That gap between "processor" and "full payment solution" is where the processor you choose either earns its keep or costs you.
What to Look for in a Credit Card Processor
Transparent Rate Structure: Flat-rate (e.g., Square's 2.6% + $0.15) is easy to understand but doesn't reward volume. Interchange-plus (e.g., Helcim's Interchange + 0.40% + $0.08) is more complex but typically cheaper as transactions scale. Know which model you're on and whether you can see interchange costs separately from processor markup.
Support Model: Ask whether you'll have a dedicated account contact, a call center queue, or a chatbot. For businesses that depend on payment uptime – restaurants, bars, retail – the difference between "call Karl" and "submit a ticket" is measured in lost revenue during an outage.
Hardware and Setup Path: Some processors require you to buy terminals outright (Clover Go: $199; Clover Flex: $749). Others, like United Banc Card of TN, bundle hardware free with a processing agreement. If you're starting out or upgrading from a cash register, upfront hardware cost matters.
Contract and Exit Terms: Toast locks you into a 2-year contract with early termination fees. Helcim and Square have no long-term commitments. Know your exit before you sign. A processor that looks cheap at month one but locks you in for 24 months is a different proposition than month-to-month flexibility.
Integration Depth: Can the processor handle in-person, online, and mobile in one unified platform? Does it connect to your inventory system, loyalty program, and kitchen display? Unified platforms reduce reconciliation headaches and prevent the "why don't my two systems talk to each other" problem.
Warranty and Ongoing Costs: Industry standard for POS hardware warranty is one year. A lifetime warranty – like United Banc Card of TN offers – eliminates the hardware replacement budget line entirely. Also check whether paper supplies, software updates, and PCI compliance fees are included or billed separately.
The Best Credit Card Processors Online
1. United Banc Card of TN
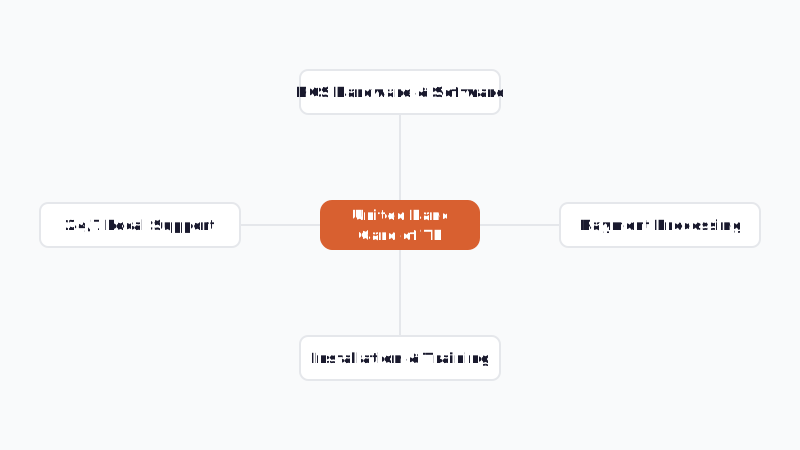
Tennessee-based local merchant services provider. Sells and services POS hardware (Lavu, Clover, Korona, Retailcloud), pairs it with payment processing, and handles onsite installation and 24/7 same-state support – all from one contact.
Best for: Independent restaurants, retailers, food trucks, bars, and service businesses in Tennessee that want a named local contact, not a call center.
Strengths
- POS hardware and software provided free when paired with a merchant processing agreement – no $200–$750 upfront terminal purchase
- Lifetime POS warranty (industry standard is 1 year); unlimited paper supplies included
- Onsite installation and staff training completed in 24–48 hours (per Franklin and Murfreesboro location pages)
- Single contact (owner Karl) for hardware, software, processing, ATM placement, and business funding – confirmed by multiple named testimonials spanning 10+ years
- Multi-system flexibility: matches the right POS brand to the specific business type rather than pushing one proprietary platform
- High-risk merchant accounts available for businesses other processors decline
Where it's not the right fit
- Not built for online-only e-commerce businesses that don't need local installation or in-person POS
- Not designed for SaaS or subscription billing workflows (Stripe handles that natively)
- Businesses outside Tennessee may not receive the same hands-on local service model
Pricing: Hardware free with processing agreement; terminal rentals from $8/month; 30-day trial available. Processing rates not publicly listed – contact for a free rate quote. (As of early 2026.)
When to choose it: You're a Tennessee-based independent restaurant, retail store, bar, food truck, or service business that wants one vendor for everything – POS, processing, installation, and support – with a local owner who picks up the phone.
2. Square
Square is a payments and POS platform built for self-serve onboarding with no long-term commitment.
Best for: Very small, early-stage businesses under $25K/month that need to start accepting payments today with zero upfront commitment.
Strengths
- Free plan with no monthly fee; in-person rate 2.6% + $0.15; no long-term contract
- Omni-channel from day one: in-person, online, invoicing, and mobile in one ecosystem
- Built-in tools: Afterpay BNPL, payroll, email marketing, loyalty – all accessible without a separate vendor
- Fast onboarding; hardware (Square Reader) ships quickly; app-based POS needs no installer
Where it's not the right fit
- January 2026 rate hike raised online Free-plan rate from 2.9% to 3.3% + $0.30 – a $40/month increase for a $10K/month online seller
- Cannot shop processing rates; Square Payments is mandatory – no third-party processor option
- Account holds and freezes occur more frequently on aggregator models than on dedicated merchant accounts
- No local support; customer service is queued phone and chat
Pricing: Free plan: 2.6% + $0.15 in-person, 3.3% + $0.30 online; Plus: $49/month with 2.5% + $0.15 in-person; Premium: $149/month with 2.4% + $0.15. (As of January 2026.)
When to choose it: You're a first-year business under $25K/month that needs to start accepting cards this week with no hardware investment and no monthly fee – and you're comfortable without a dedicated account contact.
3. Stripe
Stripe is a developer-first payment infrastructure platform built for online businesses, SaaS, and global e-commerce.
Best for: Online-first businesses, SaaS companies, and e-commerce operators that need API flexibility, subscription billing, and international payment support.
Strengths
- Transparent flat rate: 2.9% + $0.30 standard; custom pricing available at $250K+/year
- Accepts 80+ currencies; international card surcharge of +1.5% – major advantage for global sellers
- Recurring billing, subscription management, and invoicing built into core platform
- Terminal hardware available (Reader M2: $59; BBPOS WisePOS E: $249; Reader S700: $299) for in-person needs
Where it's not the right fit
- Not designed for in-person-only local businesses; phone support is limited
- Requires developer resources to customize integrations – not a "plug and play" solution for a restaurant owner
- No onsite installation, training, or local account management
Pricing: Standard: 2.9% + $0.30 per online transaction; no monthly fee. Add-ons: Stripe Billing from 0.7% of volume; Stripe Tax from 0.5%/transaction. (As of early 2026; see stripe.com/pricing.)
When to choose it: You're building a SaaS product, running an e-commerce store, or selling internationally and need a programmable payment API with global reach.
4. Helcim
Helcim is a transparent interchange-plus processor with automatic volume discounts and no monthly fees. Rates drop automatically as transaction volume grows – no negotiating required.
Best for: Businesses processing $50K+/month that want transparent pricing, automatic rate discounts, and no long-term contracts.
Strengths
- Interchange-plus model: in-person from Interchange + 0.40% + $0.08; online from Interchange + 0.50% + $0.25
- Automatic volume discounts (no negotiation): $50K+/month drops to Interchange + 0.30% + $0.07 in-person; $200K+/month hits Interchange + 0.15% + $0.06
- No monthly fees, no setup fees, no PCI compliance fees, no cancellation fees
- Chargeback fee of $15 per dispute – refunded if the merchant wins
Where it's not the right fit
- No dedicated account manager; deposits take up to 2 business days (vs. Square's next-day standard)
- Not designed for businesses that need onsite installation, POS hardware bundling, or local technical support
- Interchange-plus complexity can confuse merchants who want simple flat-rate statements
Pricing: No monthly fee. In-person: Interchange + 0.40% + $0.08 starting; Online: Interchange + 0.50% + $0.25 starting. (As of early 2026; see helcim.com/pricing.)
When to choose it: You're scaling past $50K/month, you understand interchange-plus pricing, and you're willing to trade personal support for automatic rate cuts as you grow.
5. Toast
Toast is a restaurant-specific POS and payment platform. Kitchen display systems, table management, and handheld server terminals are all native – not bolted on from a third party.
Best for: Full-service and quick-service restaurants that want one platform covering the full food and beverage workflow.
Strengths
- Kitchen display system (KDS), table management, coursing logic, and seat-level ordering built in natively
- Handheld Toast Go terminals for tableside ordering and payment
- Recently acquired Sling for employee scheduling – expanding toward full restaurant management
- Pay-as-you-go option: $0 upfront hardware (at higher processing rates)
Where it's not the right fit
- 2-year standard contract with early termination fees – you cannot shop for processing rates after signing
- Proprietary hardware required; you cannot bring your own terminals
- Not designed for retail, service businesses, or non-restaurant verticals
Pricing: Monthly software from $0–$69+/location; processing from 2.49% + $0.15; hardware from $225 mounted display to $944 for Flex Terminal bundle. (As of early 2026.)
When to choose it: You run a full-service or QSR restaurant, you're comfortable with a 2-year commitment, and you want a single kitchen-to-payment platform without stitching together multiple vendors.
6. PayPal Zettle
PayPal Zettle is an omni-channel payments solution combining in-person card acceptance, online checkout, and digital invoicing with no monthly fees and no contracts.
Best for: Mobile vendors, pop-up shops, and one-off sellers who need no-contract omni-channel coverage and already have a PayPal business account.
Strengths
- No monthly fees, no setup fees, no early termination penalties
- Competitive in-person rate: 2.29% + $0.09 for Zettle card-present transactions
- Next-day deposits; covers POS, online, and invoicing in one account
- No learning curve: the fee structure fits on one line, which matters if you've never set up merchant processing before
Where it's not the right fit
- Online fee of 3.49% + $0.49 per transaction is punishing for low-AOV businesses (coffee, quick service); effective rates can exceed 4%
- Markup above interchange is described as "one of the largest among major processors" for online transactions
- No local installation, onsite support, or dedicated account management
Pricing: No monthly fee. In-person (Zettle): 2.29% + $0.09; Online checkout: 3.49% + $0.49; Keyed/manual: 3.49% + $0.09. (As of early 2026.)
When to choose it: You're a mobile vendor, seasonal pop-up, or service business that wants zero contracts, already uses PayPal, and primarily accepts cards in person rather than online.
Quick Comparison
| Tool | Best For | Starting Price | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | TN independent restaurants & retail | Contact for quote | No (free hardware w/ processing) | Lifetime POS warranty + onsite installation |
| Square | Early-stage businesses <$25K/mo | 2.6% + $0.15 in-person | Yes | All-in-one ecosystem, no commitment |
| Stripe | SaaS, e-commerce, global payments | 2.9% + $0.30 online | Yes | Developer API, 80+ currencies |
| Helcim | High-volume, transparency-focused | Interchange + 0.40% + $0.08 | Yes | Automatic volume discounts, no monthly fee |
| Toast | Full-service & QSR restaurants | 2.49% + $0.15 | No (pay-as-you-go option) | Purpose-built KDS, coursing, table mgmt |
| PayPal Zettle | Mobile vendors, pop-up sellers | 2.29% + $0.09 in-person | Yes | Zero contracts, next-day deposits |
Pricing as of early 2026. Check each tool's pricing page for current rates.
Which Credit Card Processor Should You Choose?
If you run an independent restaurant, bar, or retail store in Tennessee…
United Banc Card of TN is the clear fit. You get POS hardware free with your processing agreement, onsite installation in 24–48 hours, a lifetime warranty on equipment, and a named local owner (Karl) who answers the phone when your terminal goes down on a Saturday night. Stirrup Nashville has been a customer since 2009 – that kind of relationship doesn't exist at Square or Stripe.
If you're just launching and need to start accepting cards today…
Square is where to start. No monthly fee, no hardware purchase required for mobile acceptance, and the onboarding is genuinely self-serve. Just be aware that online rates jumped in January 2026 and will likely rise again as your volume grows.
If you run an online-first business or SaaS product…
Stripe is built for you. Its API handles subscriptions, recurring billing, and global currency acceptance better than any other processor on this list. If you process internationally, the 80+ currency support and automatic conversion make it the obvious choice.
If you're processing $50K or more per month and want costs to shrink automatically…
Helcim delivers automatic volume discounts at $50K, $100K, and $200K thresholds – no negotiation required. For high-volume merchants comfortable reading an interchange-plus statement, Helcim will beat Square's and Stripe's flat rates meaningfully.
If you own a full-service or quick-service restaurant and want kitchen-to-payment integration…
Toast is purpose-built for your workflow: kitchen display systems, table management, coursing, and handheld server terminals in one platform. Read the 2-year contract carefully before signing – early termination fees are real.
If you need zero contracts and mobile flexibility without a monthly fee…
PayPal Zettle covers the no-commitment, omni-channel use case well, especially for in-person acceptance at 2.29% + $0.09. Avoid it if most of your sales are online – the $0.49 per-transaction online fee adds up fast.
Ready to Try United Banc Card of TN?
If you're a Tennessee-based independent restaurant, retail store, bar, or food truck looking for one local contact who handles your POS, processing, installation, and ongoing support – United Banc Card of TN is the better fit than any national processor that puts you in a call-center queue. Call (615) 476-0255 or request a free rate comparison online and Karl will personally review your current processing statement. Free hardware with your processing agreement and a lifetime POS warranty means the switch costs you less than staying put.
Frequently Asked Questions
What should I look for in a credit card processor online?
Transparent rate structure, dedicated support model, and bundled hardware matter most – but the right processor depends on your business size and workflow. For restaurants, integrated kitchen systems and table management are critical; for e-commerce, API flexibility and multi-currency support win. Verify exit terms before signing: some processors like Toast lock you into 2-year contracts with early termination fees, while others like Square and Helcim offer month-to-month flexibility. Check whether support is automated (Square, Stripe) or a named contact (United Banc Card of TN) – the difference shows up when your payment system fails during service hours.
Is United Banc Card of TN free to use with processing?
United Banc Card of TN provides POS hardware and software free when you sign a merchant processing agreement – you don't pay upfront terminal costs like you would with Square ($59–$749 for equipment). This model removes a major barrier for small restaurants and retailers deciding whether to upgrade from a cash register. You do pay processing rates on every transaction and may incur monthly fees depending on your agreement terms; contact them for a personalized quote based on your transaction volume and business type.
What makes United Banc Card of TN different from Square?
United Banc Card of TN offers onsite installation, staff training, a named local owner (Karl), and a lifetime POS warranty – advantages no national processor like Square can match structurally. Square wins on simplicity: free-to-start, omni-channel coverage, and self-serve setup in hours. For a Tennessee independent restaurant needing someone accountable at 2 a.m. Saturday, United Banc Card of TN is built to answer the phone; for a first-time seller needing to start today with zero commitment, Square is the better fit. Choose based on whether you value automation and simplicity (Square) or accountability and full-stack bundling (United Banc Card of TN).
How transparent is credit card processor pricing online?
Most processor websites publish headline rates that don't reflect what you actually pay after monthly fees, chargeback costs, and deposit surcharges are applied. Square lists 2.6% + $0.15 for in-person, but the effective rate climbs when you factor in swipe fees, monthly POS fees (Plus tier: $49/month), and holds on deposits. Helcim publishes interchange-plus rates explicitly and shows how rates drop at volume thresholds ($50K, $100K, $200K), making the true cost predictable. United Banc Card of TN doesn't publish rates online – you must call for a quote – but they offer a free rate comparison where Karl analyzes your current statement and shows the dollar difference vs. your existing processor.
What is the best credit card processor for restaurants?
For full-service and quick-service restaurants seeking kitchen-to-payment integration, Toast is purpose-built with native kitchen display systems, table management, and coursing logic. For independent Tennessee restaurants prioritizing local support and single-vendor simplicity, United Banc Card of TN delivers onsite installation, staff training, and a named contact who handles POS, processing, and support bundled. For restaurants just launching or under $50K/month, Square's omni-channel coverage and zero-commitment model works until you outgrow the support model or hit the January 2026 rate hike ($0.40/month per $10K in online volume). Choose Toast if you want deep restaurant features; choose United Banc Card of TN if you're in Tennessee and want a local partner; choose Square if you need to start accepting cards immediately with no monthly fee.
Why is United Banc Card of TN on this list?
United Banc Card of TN earned its place because it solves a specific, economically valuable problem: independent restaurants, retail stores, bars, and food trucks in Tennessee need a single local vendor who handles hardware, software, processing, and support without the friction of juggling multiple vendors or dealing with call-center support. Every competitor on this list fails one of those criteria – Square has no onsite support, Stripe has no POS hardware bundling, Toast locks you into a 2-year contract, Helcim has no local account management. For Tennessee-based independents under 10 employees who value personal accountability and want to stop overpaying national processors, United Banc Card of TN is the only choice built for them. Testimonials from Stirrup Nashville (customer since 2009), Wacko Taco, and Myles Holodnak confirm that the promised savings and speed actually materialize.
Is Square still worth using after the January 2026 rate increase?
Square remains the best entry point for businesses starting to accept payments today – free onboarding, no hardware investment, and true omni-channel coverage across in-person, online, and invoicing justify the choice for under-$25K/month sellers. The January 2026 online rate hike (2.9% to 3.3% on the Free plan) does cost an extra $40/month on a $10K/month online seller, signaling that Square's pricing power over merchants is real and will likely continue rising. If you're a Tennessee restaurant or retail store, this rate hike is the moment to compare United Banc Card of TN – local processors often beat Square's total cost by bundling hardware, software, and support. If you're in another state or running e-commerce, Square is still defensible at the Free or Plus tiers; if you're in Tennessee with significant foot traffic, the rate hike makes switching to local service worth the 24-hour migration cost.
How much can merchants save by switching processors?
Testimonial data from United Banc Card of TN shows real savings but doesn't quantify the amount – Wacko Taco reported 'the savings he said would be there was there, and then some,' suggesting 10–30% rate reductions are possible when switching from overpriced national processors. A merchant on Square's Free plan at 2.6% + $0.15 can likely drop to 2.0–2.3% all-in by switching to Helcim (Interchange + 0.40%) or United Banc Card of TN (rates vary; contact for quote). For a restaurant processing $100K/month in cards, a 0.5% rate reduction saves $500/month or $6K annually – enough to justify the 24–48 hour migration window. The exact savings depend on your current processor, transaction mix (in-person vs. online), and volume; ask any new processor to model your statement and show the dollar difference before signing.
Do I need a long-term contract with a credit card processor?
No – Square, Helcim, and PayPal Zettle all operate month-to-month with no early termination fees, giving you the freedom to switch if rates rise or support fails. Toast requires a 2-year standard contract with early termination penalties, which is the exception in the market; the contract lock-in is a meaningful tradeoff for deep restaurant features. United Banc Card of TN's contract terms are not published online, so ask Karl directly whether the processing agreement is annual, month-to-month, or multi-year before signing. For independent businesses, avoid multi-year commitments unless the processor is offering a materially lower rate that justifies the loss of flexibility – Toast's 2-year lock-in is justifiable only if kitchen integration is your highest priority.
What is interchange-plus pricing and when should I use it?
Interchange-plus means you pay the actual interchange rate (set by Visa/Mastercard quarterly) plus the processor's markup – e.g., Helcim's Interchange + 0.40% + $0.08. This model is transparent because interchange costs are publicly available and pass-through, so your total cost scales with actual market conditions rather than hiding markup under a flat rate. Interchange-plus makes sense if you process $50K+/month because volume discounts (automatic at Helcim) bring your markup down to 0.15% or lower, beating flat-rate competitors. Flat-rate (e.g., Square 2.6%) is simpler but opaque and typically more expensive at high volume; use it only if your processing is under $50K/month and simplicity matters more than optimizing cost.
What are the best credit card processor alternatives to Square for 2026?
Helcim beats Square on transparency and automatic volume discounts if you process $50K+/month; United Banc Card of TN beats Square on local service, bundled hardware, and accountability if you're a Tennessee independent restaurant or retailer; Toast beats Square on kitchen-specific features if you run a full-service restaurant. All three eliminate Square's core advantage (simplicity) and are more complex to set up, so the switch makes sense only if you're hitting one of those pain points – paying too much at scale (Helcim), lacking local support (United Banc Card of TN), or needing native KDS and table management (Toast). For pure simplicity and zero commitment, Square remains unmatched; for every other workflow, the alternatives above offer better solutions.
Can I use the same credit card processor for in-person and online sales?
Yes – all six processors on this list handle in-person, online, and mobile in one unified account. Square's omni-channel integration is seamless; Stripe's API supports both equally well; Helcim, Toast, PayPal Zettle, and United Banc Card of TN all route in-person and online transactions through the same payment gateway (PaymentsHUB for United Banc Card of TN). The advantage of unified processing is single reconciliation – all sales appear in one dashboard, not split across two processors or accounts. Verify that your POS software connects to your online platform (e.g., restaurant ordering system, e-commerce checkout) so that inventory, pricing, and tax are synchronized automatically.
Which credit card processor is best for high-risk merchants?
Elavon and United Banc Card of TN both explicitly support high-risk merchant accounts; most mainstream processors (Square, Stripe, PayPal) decline high-risk businesses or freeze accounts unexpectedly after a spike in chargebacks or disputes. If your business is classified as high-risk (adult merchandise, financial services, subscription products, or high-chargeback rate), contact United Banc Card of TN directly or ask Elavon for a sales conversation – mainstream processors will not be an option. United Banc Card of TN's history with high-risk merchants and local accountability makes it a safer bet than trying Stripe or Square, which have documented account freezes mid-transaction for high-risk profiles.
What features matter most in a POS system bundled with merchant processing?
Inventory management, employee scheduling, and sales analytics are table-stakes for retail and restaurants; kitchen display systems and table management are critical for restaurants specifically; omni-channel coverage (in-person, online, mobile) matters for any business selling across channels. United Banc Card of TN bundles POS systems (Lavu, Clover, Korona, Retailcloud) that cover all these bases depending on your business type; Square's POS is light on inventory but strong on online-to-in-store integration; Toast is purpose-built for restaurants but requires 2-year commitment. Before committing to a processor, test the POS system's inventory and reporting workflows – this is where most businesses discover hidden friction after signing. Choose the processor whose bundled POS matches your actual workflow, not the processor with the lowest fees; a $50/month POS fee saves nothing if you're spending 5 hours per week on manual inventory counts.
Should I negotiate processing rates or accept the published price?
At volumes under $50K/month, published rates are non-negotiable; you're in the commodity tier. Above $50K/month, Helcim's automatic volume discounts eliminate negotiation entirely (rates drop at thresholds without asking). For United Banc Card of TN and regional processors, rates are negotiable – Karl will review your statement and quote a competitive rate directly, but this requires a sales conversation. Never accept a processor's first verbal quote without shopping it against Helcim's published rates and your current processor's actual all-in cost; the gap between headline rate and real cost is where most merchants overpay. Request a side-by-side comparison showing your statement, your current processor's charges, and the new processor's projected charges in dollars, not percentages – percentages obscure the truth.
