TL;DR
ATM for Business Alternatives come down to how deeply your ATM needs to integrate with the rest of your business: United Banc Card of TN is the top pick for Tennessee merchants who want ATM placement bundled with POS, payment processing, and local onsite support from a single named contact. Prineta USA wins for merchants seeking the clearest 50/50 surcharge split with zero upfront cost, and ATMTrader is the right call for business owners who want to buy a machine outright and keep 100% of surcharge revenue.
ATM for Business Alternatives
ATM for Business Alternatives are worth exploring when you realize ATM for Business – while a real option for placement programs and machine purchases – leaves significant gaps: unclear surcharge splits, an aging hardware catalog that still references Windows XP and dial-up connectivity, and no integration with the POS system or payment processor you're already running. If your business operates in Tennessee and you want a single local vendor to handle ATM installation, POS, and card processing together, there are better-fit options. This page maps the right tool to the right situation.
Why People Look for ATM for Business Alternatives
Pricing opacity is the most common complaint driving merchants to search for alternatives. ATM for Business does not publish surcharge split percentages, contract lengths, or machine purchase prices anywhere on their site. A business owner evaluating whether free placement actually makes financial sense cannot run the math without a sales call – and merchants who've been burned by undisclosed fee structures before aren't eager to repeat that experience.
The hardware catalog is a second friction point. Several models listed by ATM for Business reference Windows XP operating systems and dial-up connectivity. While these machines may still function for basic cash dispensing, they create compliance exposure as networks push EMV and security upgrade requirements forward. Merchants researching a multi-year ATM investment want hardware with a credible upgrade path, not legacy components.
The third issue is isolation. ATM for Business positions its placement and purchase programs independently of any broader merchant services relationship. That's fine for a business that simply wants a cash machine in the corner – but for restaurant and retail operators who are already managing POS inventory, payment processing, and staff analytics, a standalone ATM vendor creates yet another support line, another settlement statement, and another contact to chase when something goes wrong at 10 PM on a Saturday.
What to Look for in an ATM Solution
Surcharge split transparency. The surcharge split is the core economics of any free placement program. A 50/50 split on a $3.00 surcharge yields $1.50 per transaction; a 20% split yields $0.60. Over 150 monthly transactions, that's a $135/month difference. Get the exact percentage in writing before signing anything.
Integration with your existing POS. If your business runs a cloud-based POS (Clover, Lavu, Toast, Square), ask whether the ATM provider can connect cash flow data to your existing dashboard. Seeing card revenue, cash withdrawals, and inventory in one place makes reconciliation faster and cuts down on end-of-day guesswork.
Hardware currency. Verify that any machine being placed or sold runs current EMV-compliant firmware and TCP/IP connectivity (not dial-up), and that the manufacturer still pushes software updates. Genmega and Hyosung are the two dominant retail manufacturers; both have current-generation models with solid service networks.
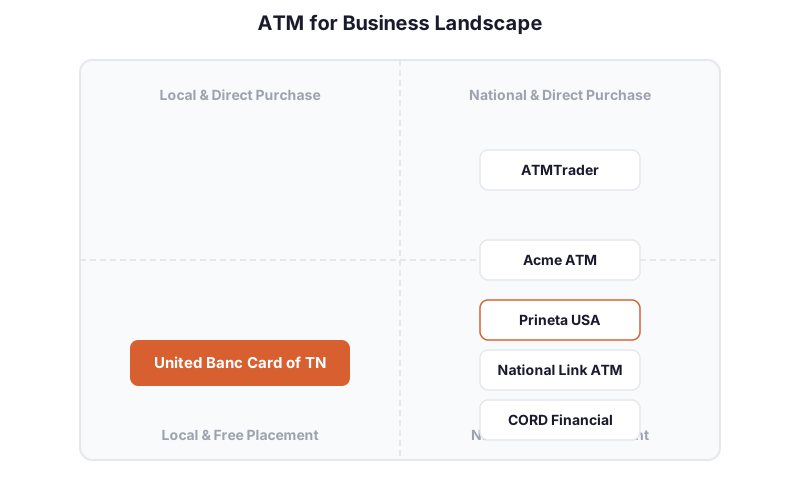
Local vs. national service coverage. National placement companies (Prineta, National Link, CORD) can service machines across multiple states. Local providers have faster physical response times, a named technician, and accountability tied to an actual relationship – not a call center queue.
Contract terms and exit flexibility. Free placement programs typically require exclusivity on ATM surcharge revenue and may lock you into multi-year agreements. Know the early termination terms before signing, and confirm whether the ATM can be removed if you sell the business or change locations.
Setup speed. ATM placement that takes 3–6 weeks for paperwork and installation creates real cash flow delay. Confirm installation timelines upfront – the best local operators can complete installation within 48 hours of agreement.
The Best ATM for Business Alternatives
1. United Banc Card of TN
United Banc Card of TN is a Tennessee-based local merchant services provider that bundles ATM placement and sales with POS systems (Lavu, Clover, Korona, Retailcloud), payment processing, and business funding – all managed by a single owner who handles installation and support directly.
Best for: Independent Tennessee restaurants, bars, retail stores, and hospitality businesses that want one local contact for ATM, POS, and payment processing instead of three separate vendor relationships.
Strengths
- Karl (owner) personally manages ATM placement, installation, and ongoing support – no 1-800 number, no regional franchise intermediary
- ATM service integrates directly with POS and payment processing; cash flow, surcharge revenue, and card transactions visible in one place
- Onsite installation typically completed within 24–48 hours; staff training included
- 10+ years in market with documented long-term customer relationships (Stirrup Nashville since 2009, Mounir Kasawat since 2011)
- Full-stack accountability: one contract covers POS hardware, merchant processing, ATM, and business funding through GoKapital
- Lifetime warranty on POS systems; that coverage extends to the hardware itself
Where it's not the right fit
- Primarily serves Tennessee; merchants outside the state needing multi-location ATM coverage should use a national placement provider
- ATM surcharge split terms are not publicly disclosed – merchants optimizing purely for ATM revenue should compare directly against Prineta's published 50/50 model
- Not designed for large franchise operators managing 20+ ATMs across multiple states
Pricing: Terminal rentals from $8/month; POS hardware provided free with merchant processing agreement. ATM placement and purchase pricing available via direct consultation at (615) 476-0255. As of mid-2025.
When to choose it: You're a Tennessee restaurant, bar, or retail business already frustrated by national processor fees, slow support, and disconnected systems – and you want a local expert who will install your ATM, set up your POS, and answer the phone when something breaks.
Get a free quote from United Banc Card of TN →
2. Prineta USA
Prineta USA is a national ATM placement company offering two transparent programs: full-service free placement (Prineta handles cash fill and maintenance) and a merchant-loaded 50/50 revenue share where the business owner loads cash and keeps half of every surcharge.
Best for: Merchants outside Tennessee, or any business wanting clearly published surcharge split economics without a processor switching requirement.
Strengths
- 50/50 surcharge split on merchant-loaded program is explicitly disclosed – $1.50 of every $3.00 surcharge goes to the merchant
- Merchant can raise the surcharge (e.g., to $6.00) and keep $4.00 per transaction on the loaded program
- Full-service option requires zero cash loading or maintenance from the merchant
- Nationwide coverage; no geographic restriction
- Customer reviews back this up: Sofia Sanin of Sol Cafe said, "Loved working with them. Installed ATM in my new business and everything is working great."
Where it's not the right fit
- ATM is standalone – no POS integration, no card processing bundle, no local installation team
- Merchant-loaded program requires active cash management, which adds operational overhead for busy food service operators
- National service model means physical support response time is slower than a same-state provider
Pricing: Free placement programs available at no upfront cost; surcharge splits as noted above. Check Prineta's site for current program terms. As of mid-2025.
When to choose it: You want the clearest surcharge split math in the market, you're not in Tennessee, or you're happy with your current POS and processor and just need a cash machine with no strings attached.
3. Acme ATM
Acme ATM offers a dual model: free placement with a 50% surcharge revenue split, or direct machine purchase starting at $2,395 for a Genmega 2500 (as of mid-2025).
Best for: Merchants who want the flexibility to choose between placement and ownership, with published hardware pricing and a clear revenue model.
Strengths
- Direct purchase pricing is published: Genmega 2500 from $2,395, Hyosung Halo II available as premium option
- Free placement program offers 50% surcharge split with full installation, programming, and maintenance
- EMV chip readers and fraud-prevention cameras standard on hardware sold
- High-capacity 1,000-note cassettes reduce restocking frequency
- Responsive customer service noted in reviews; well-suited to merchants new to ATM operations
Where it's not the right fit
- National service model; not designed for merchants who need same-day local troubleshooting
- No POS or payment processing integration; ATM revenue is tracked separately
- Ownership model requires merchant to manage cash loading, paper restocking, and basic maintenance
Pricing: Free placement (50% surcharge split) or direct purchase from $2,395 (Genmega 2500) to $4,619+ (Genmega GT3000 through-the-wall). As of mid-2025. Check Acme ATM pricing for current inventory.
When to choose it: You've decided to own a machine outright and want published hardware prices with a real revenue projection – or you want a 50/50 split placement without switching your payment processor.
4. National Link ATM
National Link ATM is a national full-service placement company. They handle cash loading, maintenance, and repairs, and pay monthly commissions to the host business. Their reporting dashboard is built for retail, restaurant, hotel, and liquor store operators managing multiple machines.
Best for: Multi-location retail chains, hotels, and franchises that need national ATM coverage with centralized reporting.
Strengths
- Real-time monitoring and advanced profit-sharing reporting built into the placement program
- Monthly commission settlements; transparent reporting dashboard
- Full-service model: cash loading, receipt paper, repairs, and technical support all handled by National Link
- Active deployments across convenience stores, beauty salons, gas stations, liquor stores, and hospitality venues
- Nationwide coverage; no state restriction
Where it's not the right fit
- Surcharge split percentages are not publicly disclosed – typical national placement splits run 20–30% to merchant, which is below Prineta and Acme's 50% programs
- Not designed for merchants wanting ATM bundled with POS or payment processing
- Single-location independent operators may find national operators less attentive than local providers
Pricing: Free placement (no upfront cost); commission split not publicly disclosed. Contact National Link at (877) 286-4242 for current terms. As of mid-2025.
When to choose it: You operate multiple locations across states and need a single ATM partner with centralized reporting and nationwide service capacity.
5. ATMTrader
ATMTrader is a direct ATM sales platform. Their published pricing and spec-matching guide breaks down hardware models by specific business type – one of the few places you can actually compare machines before picking up the phone.
Best for: Business owners who want to buy a machine outright, keep 100% of surcharge revenue, and select hardware based on published specs matched to their specific venue type.
Strengths
- Most transparent pricing in the category: Genmega G2500 from $2,549, Onyx-W wall-mount from $2,969, GT3000 through-the-wall from $4,619, Hyosung Halo II from $2,599 – all published (as of mid-2025)
- Business-type matching guide covers retail stores, laundromats, bars, gas stations, dispensaries, hotels, and high-volume locations
- Free shipping on most models
- Real ROI guidance: surcharge revenue of $2.50–$4.00/withdrawal, many operators recover machine cost within the first year at average transaction volumes
- No placement contract, no revenue split – merchant owns machine and keeps full surcharge less network fees ($0.10–$0.50/transaction)
Where it's not the right fit
- Ownership means merchant is responsible for cash loading, paper restocking, and maintenance
- No placement service, no cash management, no ongoing support contract
- Not suited for merchants who want passive income without operational involvement
Pricing: Direct purchase from $2,395 (Genmega 2500 basic) to $7,669+ (GT5000 high-volume through-the-wall). Note: Genmega announced multi-unit price increases effective June 2025. As of mid-2025 – verify current pricing at ATMTrader.
When to choose it: You want to own your machine, understand the ROI math clearly, and are willing to manage daily cash operations in exchange for keeping the full surcharge revenue stream.
6. CORD Financial Services
CORD Financial Services is a national ATM placement company. Their free placement program covers installation, maintenance, and cash loading – the business owner just collects monthly commission deposits.
Best for: Super centers, convenience stores, and hospitality venues that want ATM operations handled entirely by a national provider.
Strengths
- Full installation and ongoing maintenance included at no cost
- Real-time monitoring capabilities and advanced profit-sharing reporting
- Monthly commission payments to business owner
- Covers super centers, convenience stores, hospitality, nightlife, and banking locations
- Nationwide coverage with regional offices
Where it's not the right fit
- Specific surcharge split percentages and placement qualification criteria not disclosed publicly
- No POS or merchant processing integration
- Not optimized for single-location independent operators seeking a local relationship
Pricing: Free placement; commission split terms not publicly disclosed. Contact CORD directly at cordfinancial.com for current program details. As of mid-2025.
When to choose it: You run a convenience store, hotel, or nightlife venue and want a national operator managing the ATM entirely – cash, maintenance, repairs – while you collect monthly commission deposits and check the reporting dashboard.
Quick Comparison
| Tool | Best For | Starting Price | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | Tennessee merchants wanting ATM + POS + processing bundled | $8/mo terminal rental | Yes (with processing agreement) | One local owner handles ATM, POS, and processing |
| Prineta USA | Merchants wanting a transparent 50/50 split | $0 placement | Yes (free placement) | Published 50/50 surcharge split, merchant controls surcharge rate |
| Acme ATM | Businesses choosing between placement and ownership | $2,395 purchase | Yes (50% split placement) | Published hardware prices with EMV-standard machines |
| National Link ATM | Multi-location chains needing national coverage | $0 placement | Yes (free placement) | Real-time monitoring with centralized fleet reporting |
| ATMTrader | Owners wanting 100% surcharge and published specs | $2,549 purchase | No | Most detailed hardware spec-matching guide in market |
| CORD Financial | Convenience stores and hospitality venues | $0 placement | Yes (free placement) | Nationwide full-service placement with profit-sharing reporting |
Pricing as of mid-2025. Check each provider's pricing page for current rates.
Which Alternative Should You Choose?
Most small business owners searching this page want the simplest path to ATM revenue. Here is who wins in each scenario.
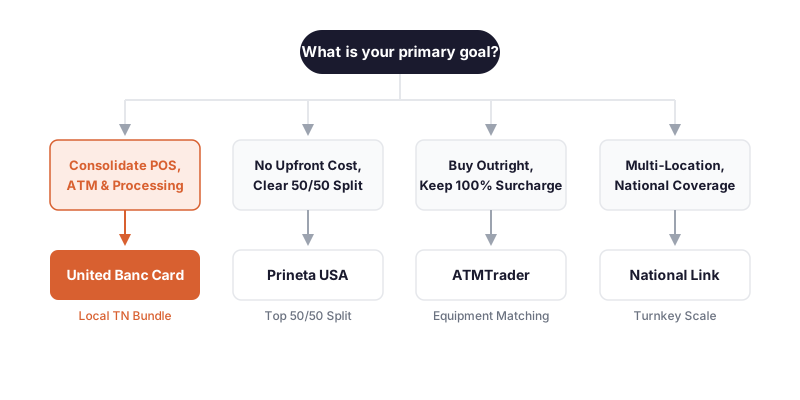
If you want zero upfront cost and the clearest revenue math…
Prineta USA is the right choice. Their 50/50 merchant-loaded program is the only major free placement option with the surcharge split published on the website. You can calculate your income before signing anything.
If you want to buy a machine outright and keep 100% of surcharge revenue…
ATMTrader gives you the most detailed published pricing and spec-matching by venue type. A Genmega G2500 at $2,549 in a bar averaging 150 transactions/month at a $4.00 surcharge returns the machine cost in under five months.
If you need national ATM coverage across multiple states or locations…
National Link ATM or CORD Financial are built for scale. National Link's real-time monitoring and centralized commission reporting are designed for fleet operators; CORD specializes in hospitality and super-center deployments nationwide.
If you're a Tennessee restaurant, bar, or retail business that wants ATM integrated with your POS and payment processing…
United Banc Card of TN is the better fit. Karl handles ATM installation alongside your Clover, Lavu, or Korona POS setup, so your surcharge revenue, card transactions, and inventory are visible in one place instead of three separate dashboards. Setup completes in 24–48 hours, and you have a local number to call instead of a national queue. Stirrup Nashville has been a customer since 2009 – that kind of long-term relationship doesn't happen with a 1-800 number.
If you already have a POS and processor you're happy with and just need an ATM…
Prineta or Acme ATM are the clean options – free placement, no processor-switching requirement, and a defined revenue split. No disruption to your existing setup.
Ready to Try United Banc Card of TN?
If you're a Tennessee merchant tired of juggling three separate vendors for your ATM, POS, and payment processing – United Banc Card of TN is the right call. One conversation with Karl gets you a quote on ATM placement, a POS system matched to your business type, and a processing rate comparison against what you're paying now. Call (615) 476-0255 or request a free proposal at unitedbanccardoftn.com. Setup typically completes within 48 hours, and there's no obligation to the quote.
Frequently Asked Questions
What should I look for in an ATM placement program for my small business?
The most important factors are surcharge split transparency, integration with your existing POS system, and hardware currency that supports EMV and TCP/IP connectivity. A clear surcharge percentage in writing before signing is essential-the difference between a 50/50 split and a 20% split on $3.00 surcharges equals $135 per month over 150 transactions. Local service response time and contract exit flexibility also matter significantly, especially if your business location changes or you sell.
What is the best ATM for small business if I want zero upfront cost?
Prineta USA and Acme ATM both offer free placement programs with no upfront investment. Prineta explicitly publishes a 50/50 surcharge split on their merchant-loaded program, so you can calculate your income before signing. Acme offers a similar 50% split with full installation and maintenance included, making either a solid choice if you want to avoid ownership costs and hardware management.
Should I buy an ATM machine or use a free placement program?
Ownership makes sense if you want 100% of surcharge revenue (less network fees) and are willing to manage daily cash loading and maintenance-ATMTrader publishes hardware pricing starting at $2,549 (Genmega G2500), with typical ROI timelines of 6–12 months at average transaction volumes. Free placement is better if you prefer passive income with zero operational overhead and are comfortable with a 20–50% revenue split depending on the provider. The right choice depends on whether you'd rather own the asset or delegate all operations to the placement company.
Can I integrate an ATM with my existing POS and payment processing?
Most national ATM placement companies (Prineta, Acme, National Link) operate independently of your POS, creating separate reporting for cash withdrawals and card transactions. United Banc Card of TN is unique for Tennessee merchants because they bundle ATM placement directly with POS systems (Lavu, Clover, Korona) and merchant processing, so surcharge revenue, card transactions, and inventory appear in one dashboard. This integration eliminates end-of-day reconciliation headaches but requires switching both your processor and POS if you're currently using another vendor.
How long does ATM installation typically take?
National placement companies (Prineta, Acme, National Link, CORD) usually complete installation within 2–4 weeks after contract approval due to underwriting and regional technician scheduling. United Banc Card of TN completes onsite installation within 24–48 hours for Tennessee merchants because Karl personally manages the process locally. Setup speed matters if cash flow timing is critical-local providers win on responsiveness, while national operators prioritize compliance and standardized workflows.
What is the difference between a full-service ATM placement and a merchant-loaded program?
Full-service placement means the company handles all cash loading, maintenance, and repairs-you collect a monthly commission with zero operational work. Merchant-loaded programs require you to fill the machine with cash regularly but pay a higher surcharge split, typically 50% versus 20–30% on full-service. Full-service is better for busy restaurant and retail operators; merchant-loaded suits owners with spare time who want to maximize surcharge income.
Is ATMTrader or ATM for Business the better option to buy a machine?
ATMTrader publishes transparent hardware pricing ($2,549 for a Genmega G2500, $4,619 for a GT3000) with spec-matching guides by business type, making ROI calculations straightforward before purchase. ATM for Business lists some models but does not publish prices on their website and references older hardware with Windows XP operating systems, creating compliance concerns for long-term deployments. ATMTrader is the clearer choice if you want to own a machine outright-you can compare models and costs immediately without a sales call.
Which ATM provider is best for a multi-location business operating across multiple states?
National Link ATM and CORD Financial Services both offer nationwide coverage with centralized fleet reporting, making them designed for convenience stores, hotels, and chain operators managing 10+ machines. United Banc Card of TN is primarily Tennessee-focused, so it's not suited for multi-state expansion. National Link's real-time monitoring dashboard and profit-sharing reporting are optimized for large-scale deployments, while CORD specializes in hospitality and super-center models.
What is the typical surcharge split when using a free ATM placement program?
Prineta USA and Acme ATM both offer transparent 50% surcharge splits on free placement programs-meaning $1.50 of every $3.00 surcharge goes to the merchant. National Link and CORD Financial do not publish their splits publicly, but industry benchmarks typically range from 20–30% on full-service national placements. Always get the exact percentage in writing before signing anything, as this is the core economics determining whether an ATM investment makes financial sense for your business.
Why would I choose United Banc Card of TN over a national ATM placement company?
United Banc Card of TN wins for Tennessee restaurants, bars, and retail businesses that want a single local vendor handling ATM placement, POS installation, payment processing, and 24/7 support from named owner Karl. One contract replaces three separate vendor relationships and integrates surcharge revenue with card transactions and inventory in one dashboard. Onsite installation within 24–48 hours and a 10+ year track record with long-term customer relationships (Stirrup Nashville since 2009) create accountability that national 1-800 call centers cannot match.
Is ATM for Business still worth considering, or are the alternatives clearly better?
ATM for Business remains relevant if you want a standalone ATM transaction without committing to a processor relationship-no switching required. However, the site does not publish surcharge split percentages, contract terms, or current hardware pricing, making it difficult to evaluate costs upfront. Competitors like Prineta, Acme, and ATMTrader publish all key terms transparently, so most merchants searching for alternatives find clearer financial math elsewhere-especially if hardware currency and integration matter to your business model.
What is the average payback period for buying an ATM machine versus using free placement?
Ownership typically pays back within 6–12 months depending on transaction volume and surcharge rates-a Genmega G2500 ($2,549) at a bar averaging 150 transactions/month at $4.00 surcharge breaks even in roughly five months. Free placement yields lower per-transaction income (20–50% split) but requires zero capital outlay and operational overhead. The financial choice depends on whether you have $2,500–$5,000 capital available and time to manage daily cash operations-if neither, free placement is faster to profitability even if the per-transaction margin is lower.
Can I raise the surcharge amount on a Prineta merchant-loaded program?
Yes-Prineta's merchant-loaded program allows you to set your own surcharge rate, so raising it from $3.00 to $6.00 increases your 50% share from $1.50 to $3.00 per transaction. This flexibility is one of Prineta's main advantages over full-service placement, where the surcharge amount is typically set by the placement company. However, aggressive surcharge rates (above $5.00) may reduce transaction volume as customers seek ATMs with lower fees elsewhere.