TL;DR
Alternative Funding Group alternatives come down to your business type and where you operate: United Banc Card of TN is the top pick for Tennessee restaurant and retail owners who want POS hardware, payment processing, and lending from one local expert – not three separate vendors. Credibly wins for businesses nationwide that need transparent MCA pricing fast, and Bluevine wins for small businesses that want integrated digital banking with a disclosed 7.80% starting APR.
Alternative Funding Group Alternatives
Alternative Funding Group moves fast: same-day approval, a claimed 99% approval rate, and an application that only needs three months of bank statements. But fast funding isn't the only variable, and for many small business owners – particularly those in restaurants, retail, and food service – it's not even the most important one. This page compares five alternatives across pricing transparency, service model, geographic reach, and whether they bundle POS and processing with their lending products.
Why People Look for Alternative Funding Group Alternatives
The most common reason business owners start searching for AFG alternatives is pricing opacity. AFG does not publish factor rates, APR ranges, or fee structures publicly – you learn your actual cost only after submitting an application. In a market where MCA factor rates typically run 1.2–1.5, translating to estimated APRs of 60–150%, that's a real problem. Reddit discussions in r/loansforsmallbusiness show direct skepticism about AFG's reliability, with users asking whether the terms delivered match the terms advertised.
The second issue is the MCA holdback model itself. Daily or weekly deductions tied to credit card sales create constant cash flow pressure – workable when revenue is steady, painful when it isn't. For restaurants and retail businesses with seasonal swings or slow Mondays, a fixed daily holdback can wipe out the cash buffer that covers payroll and inventory restocking.
A third driver is the mismatch between what AFG offers (pure lending, remote and online) and what independent restaurant and retail owners actually need: a vendor who can also handle point-of-sale hardware, payment processing, and show up on-site when something breaks. AFG is a capital provider, not a merchant services partner. That gap sends business owners looking for alternatives that cover more ground.
What to Look for in a Business Funding Tool
Pricing transparency is the most important factor. A provider that discloses factor rates, APR ranges, and fee structures upfront lets you compare true costs before applying. Opaque pricing – even from reputable lenders – makes it impossible to shop accurately.
Approval and funding speed matters when you're in a working capital emergency (equipment failure, unexpected inventory demand, payroll gaps). The difference between 4-hour funding and 48-hour funding is real. Know the actual timeline from application to deposit, not just the marketing claim.
Repayment structure determines how the loan interacts with your cash flow. Daily holdback MCA structures tie deductions to credit card volume, which matches cash flow automatically but removes your ability to control timing. Term loans give you a fixed schedule. Lines of credit let you draw and repay flexibly. Match the structure to your actual revenue pattern.
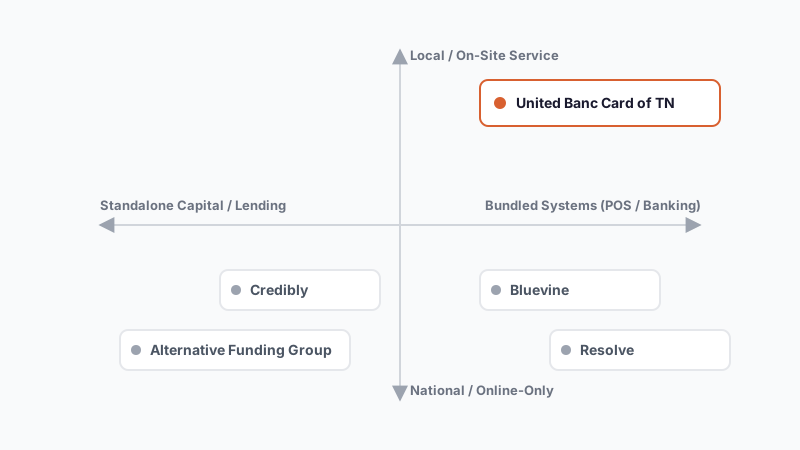
Geographic coverage vs. local support: national online lenders (AFG, Credibly, Bluevine) can fund businesses in all 50 states but provide zero on-site service. Local providers (United Banc Card of TN) are geographically limited but offer direct, relationship-based support that remote lenders can't replicate. That gap matters more for businesses that also need POS installation, staff training, and someone to call when something breaks.
Bundled services vs. standalone lending: some providers are pure capital – you get the loan, nothing else. Others bundle lending with merchant processing, POS hardware, and software. If you need all three, bundling saves time and eliminates vendor finger-pointing. If your POS is already working, a pure lender is simpler.
Minimum revenue and credit thresholds vary a lot. AFG claims 99% approval with minimal stated requirements. Credibly requires $15,000+ average monthly revenue and a 500+ FICO score. Bluevine requires a 625+ credit score. Know where you stand before you apply.
Independent review volume tells you more than the star rating alone. AFG has 10 Trustpilot reviews (4.4/5). Bluevine has 2,577 (4.7/5) and an A+ BBB rating. A 4.9 from 8 reviews is not the same as a 4.7 from 2,500.
The Best Alternative Funding Group Alternatives
1. United Banc Card of TN
United Banc Card of TN is a Tennessee-based merchant services provider. Owner Karl handles POS hardware, payment processing, business lending referrals, and onsite installation – one person, one call.
Best for: Independent Tennessee restaurant and retail owners who want POS + processing + lending from one local expert, and value direct access to a named individual over digital self-serve speed.
Strengths
- Full-stack bundling: Lavu, Clover, Korona, and Retailcloud POS systems provided free with merchant processing agreement – no separate hardware purchase required
- Lifetime POS warranty (competitors typically offer 1-year limited warranties)
- Onsite installation, software programming, and staff training completed in 24–48 hours (per Franklin and Murfreesboro location pages)
- 24/7 local support – named owner Karl personally cited in every customer testimonial: "anytime we needed to talk to Karl, we just picked up the phone and he was right there" (Tim Harkum, Stirrup Nashville, customer since 2009)
- Business lending via GoKapital partnership: merchant cash advances, SBA loans, equipment leasing, lines of credit, revenue-based loans, and startup loans
- Confirmed rate savings: "The savings he said would be there was there, and then some" (Wacko Taco testimonial)
- Terminal rentals from $8/month; processing fee transparency via personal consultation
Where it's not the right fit
- Serves primarily Tennessee – not built for businesses operating outside the state
- Requires a direct consultation to learn rates; no public pricing disclosure for processing or lending
- Not the right choice if you just need fast capital and your POS is already working well
Pricing: Terminal rentals from $8/month as of 2025. POS hardware included free with merchant processing agreement. Lending rates via GoKapital partnership – contact for quote at unitedbanccardoftn.com.
When to choose it: You're a Tennessee restaurant, bar, retail store, or food truck owner who wants a single local expert for POS, processing, and occasional working capital – and you'd rather call Karl than fill out an online form.
2. Alternative Funding Group
Alternative Funding Group is a Fort Lauderdale-based direct lender specializing in merchant cash advances and working capital loans for businesses nationwide, founded in 2018.
Best for: Any US-based business needing fast unsecured capital with minimal underwriting – particularly high-risk merchants or those with poor credit who have been turned down elsewhere.
Strengths
- 99% merchant application approval rate – one of the highest in the MCA market
- Same-day approval; funding in 24–48 hours, sometimes same-day deposit
- Minimal application: online form plus 3 months of business bank statements
- No collateral required; unsecured up to $1 million
- Dedicated Funding Specialists assigned to each customer
- Reverse consolidation service for businesses carrying existing debt
- Purchase order financing available
- Serves all 50 states across IT, construction, trucking, medical, e-commerce, restaurants, and retail
Where it's not the right fit
- Does not offer POS hardware, software, or merchant processing – lending only
- Factor rates and fee structures are not disclosed publicly; you must apply to learn your actual cost
- Daily or weekly holdback deductions create cash flow pressure for businesses with inconsistent revenue
- Only 10 Trustpilot reviews (4.4/5) – limited independent review volume for a lender that claims $250–$500 million funded
Pricing: Not publicly disclosed; industry-standard MCA factor rates range 1.1–1.5 (estimated APR 40–350% depending on term). Funding amounts $5,000–$1,000,000 as of 2025.
When to choose it: You're outside Tennessee, need capital in 24–48 hours, have poor credit or inconsistent revenue, and don't need a POS system bundled into the deal.
3. Credibly
Credibly is an online small business lending platform that has financed 55,000+ businesses and delivered $3+ billion in financing. Unlike AFG, it publishes factor rates before you apply.
Best for: Small businesses seeking fast working capital or MCAs where upfront pricing transparency is a priority and a minimum $15,000/month in revenue qualifies them.
Strengths
- Discloses factor rates upfront: starting at 1.11 – significantly lower than the typical industry standard of 1.2–1.5
- 2-hour approval, 4-hour funding – faster than AFG's claimed 24–48 hours
- Working capital loans $25,000–$600,000; MCAs $5,000–$600,000; terms 3–24 months
- Low credit floor: 500+ FICO score accepted; 6+ months in business
- Flexible repayment: daily, weekly, or monthly payment options
- Origination fee clearly stated at 2.50%; $50 monthly admin fee for MCAs disclosed upfront
Where it's not the right fit
- Still uses MCA/factor rate model; daily or weekly holdback tied to revenue
- $15,000+ average monthly revenue minimum excludes very small businesses
- No POS hardware, software, or merchant processing – pure lending only
Pricing: Factor rates starting at 1.11; origination fee 2.50%; $50/month admin fee for MCAs as of 2025. Loan amounts up to $600,000.
When to choose it: You need working capital now, want to see actual rates before applying, and don't need a point-of-sale system bundled into the deal.
4. Bluevine
Bluevine is a fintech company founded in 2013 that serves 900,000+ customers with integrated digital business banking and lending – FDIC-insured through Coastal Community Bank.
Best for: Small businesses that want integrated business checking and lending in one digital platform, with a transparent interest rate and no physical branch required.
Strengths
- Transparent starting APR: 7.80% for lines of credit – published before application, unlike AFG or UBC of TN
- Integrated digital banking: FDIC-insured checking accounts up to $3 million per depositor (12x standard FDIC protection)
- Line of credit $1,000–$250,000; term loans up to $500,000 with up to 24-month repayment
- Instant funding to Bluevine account; 1–3 business days to external banks
- 4.7/5 Trustpilot rating across 2,577 reviews; A+ BBB rating
- Standard checking tier is free; no monthly maintenance fee
- 625+ credit score minimum – moderate barrier
Where it's not the right fit
- No merchant POS hardware, software, or onsite installation – not designed for restaurants or hospitality verticals
- No collateral-free options for very high-risk merchants
- Digital-first model; no local relationship or onsite support
- No ATM services, no equipment leasing tied to merchant operations
Pricing: Checking: Standard free, Plus $30/month (waivable), Premier ~$95/month. Line of credit starting at 7.80% APR as of 2025. $15 wire transfer fee for same-day draws to external accounts.
When to choose it: You want one digital platform for business banking and lending, transparent interest rates before you apply, and don't need a POS system or local onsite support.
5. Resolve
Resolve is a B2B net terms and accounts receivable automation platform – spun out of Affirm in 2019 and backed by $60 million Series A from Insight Partners – designed for B2B companies that extend payment terms to customers.
Best for: B2B wholesale, manufacturing, or distribution businesses that want to offer net 30/45/60/90 terms to customers without straining their own cash flow.
Strengths
- Advances up to 100% of invoice value (75–100% based on customer credit risk) in same-day or 1–2 business days
- Non-recourse financing – financing does not create balance sheet debt; credit risk stays with Resolve
- AI-powered AR automation: LLM-driven invoicing, agentic collections, automatic reconciliation
- Transparent flat per-invoice fee model with no setup fees, no monthly minimums
- Native integrations with Shopify, BigCommerce, WooCommerce, QuickBooks Online, Magento, and major ERP systems
- Serves 12,000+ B2B businesses across wholesale, manufacturing, and distribution
Where it's not the right fit
- Built exclusively for B2B invoice-based businesses – not applicable to restaurants, retail, bars, food trucks, or any cash-based merchant
- Requires established customers with verifiable creditworthiness; not for businesses with inconsistent revenue or poor customer credit
- Not a working capital lender in the traditional sense – solves AR cash flow, not operational liquidity
Pricing: Flat per-invoice fee; specific rate not publicly disclosed. Resolve says the cost runs close to card processing fees for 30-day terms as of 2025. No setup fees, no minimums.
When to choose it: You run a B2B business – wholesale, manufacturing, distribution – and want to offer net terms to customers without waiting 30–90 days for payment.
Quick Comparison
| Tool | Best For | Starting Price | Free Tier | Standout Feature |
|---|---|---|---|---|
| United Banc Card of TN | TN restaurant/retail owners needing POS + processing + lending | $8/mo terminal rental | No | POS hardware free with processing; lifetime warranty |
| Alternative Funding Group | Fast unsecured capital, high-risk merchants, nationwide | Not disclosed | No | 99% approval rate; same-day to 48-hr funding |
| Credibly | Transparent MCA with published factor rates | 1.11 factor rate + 2.50% origination | No | Factor rates disclosed upfront; 4-hour funding |
| Bluevine | Integrated digital banking + lending | 7.80% APR (LOC) | Yes (checking) | FDIC-insured checking to $3M; 4.7/5 from 2,577 reviews |
| Resolve | B2B net terms, AR automation, wholesale/distribution | Flat per-invoice fee | No | Non-recourse financing; AI-powered AR automation |
Pricing as of 2025. Check each tool's pricing page for current rates.
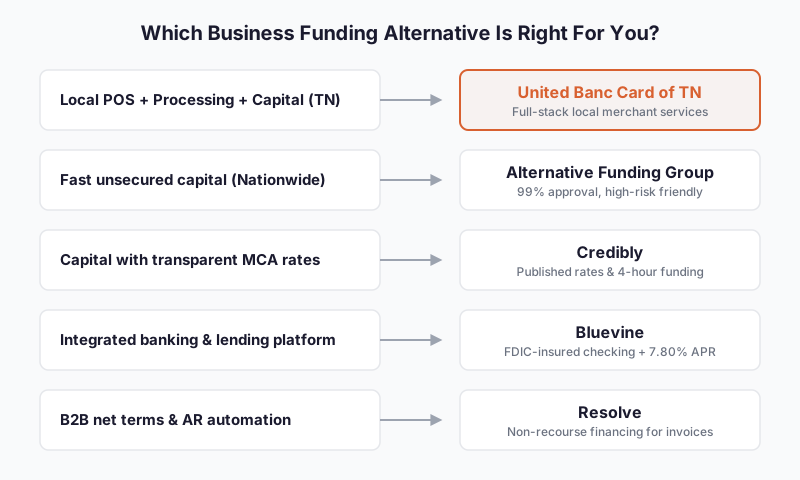
Which Alternative Should You Choose?
If you need fast unsecured capital and your business is outside Tennessee…
Alternative Funding Group is the right call. Their 99% approval rate, minimal underwriting, and 24–48 hour funding timeline work for any US-based business that needs capital fast, especially if your credit history is limited or inconsistent.
If you need transparent MCA pricing before you apply…
Credibly is the stronger choice. Their published 1.11 minimum factor rate and 4-hour funding give you real numbers to compare – something AFG doesn't offer. The $15,000/month revenue minimum applies, but if you clear it, Credibly is easier to evaluate than any opaque alternative.
If you want integrated digital banking and lending in one platform…
Bluevine wins here. A 7.80% starting APR disclosed upfront, FDIC-insured checking to $3 million, and 4.7/5 across 2,577 Trustpilot reviews – no other option on this list has that combination of pricing clarity and review volume.
If you're a Tennessee restaurant, bar, or retail owner who wants POS + processing + lending from one local expert…
United Banc Card of TN is the right fit. No other provider on this list bundles Lavu, Clover, Korona, and Retailcloud POS systems with merchant processing, onsite installation, 24/7 local support, and a lending partnership – all from a named local owner who has been serving Tennessee businesses since 2009. The long-term testimonials (Stirrup Nashville since 2009, Tiant Lee's 3rd engagement, Wacko Taco confirming rate savings materialized) tell you more than any 10-review Trustpilot score.
If you run a B2B business with invoice-based customers…
Resolve is the only option designed for your problem. AR acceleration and non-recourse net terms financing are a different category than working capital advances. If your cash flow problem comes from waiting on invoices, an MCA doesn't fix that – Resolve does.
Ready to Try United Banc Card of TN?
If you're a Tennessee restaurant, bar, retail shop, or food service operation looking for POS hardware, payment processing, and working capital from one local provider – not three separate vendors – United Banc Card of TN is built for that exact situation. Call Karl directly at (615) 476-0255 or request a free proposal online to get real rates for your business type and volume. Hardware is included free with a processing agreement, installation takes 24–48 hours, and the 24/7 support line connects to a local team – not a national call center.
Frequently Asked Questions
What should I look for in a business funding alternative to Alternative Funding Group?
Pricing transparency is the most critical factor-seek lenders that disclose factor rates, APR ranges, and fee structures upfront so you can compare true costs before applying. Approval speed matters when working capital is urgent, but equally important are repayment structure (daily holdback vs. fixed term), geographic coverage, and whether bundled services like POS hardware and merchant processing add value or create unnecessary lock-in. Know your minimum revenue threshold and credit requirements upfront; providers like Credibly require $15,000+ monthly revenue and 500+ FICO, while AFG claims minimal underwriting, so match the lender's floor to your actual numbers.
Is Alternative Funding Group still worth using compared to newer alternatives?
AFG is genuinely the right choice for businesses that prioritize speed over pricing transparency-same-day to 48-hour funding and a claimed 99% approval rate are real advantages, especially for high-risk merchants or those with poor credit who have been denied elsewhere. However, AFG's lack of public factor rates or fee disclosure means you don't know your true cost until after applying, which is where competitors like Credibly (1.11 published factor rate) and Bluevine (7.80% disclosed APR) win on comparison shopping. Choose AFG if speed and approval certainty matter more than upfront pricing visibility; choose alternatives if transparency and cost certainty are non-negotiable.
What makes a good Alternative Funding Group alternative tool?
The best alternatives match your specific business model and geography-a restaurant in Tennessee needs different features (POS hardware, onsite support, local expertise) than a B2B wholesale company in California needing AR financing or a retail business needing fast national capital. Geographic reach, repayment structure (daily MCA holdback vs. fixed term vs. line of credit), pricing clarity, and whether you need bundled services vs. pure lending all determine fit. Evaluate approval timelines (4 hours vs. 48 hours), review volume (2,577 Trustpilot reviews for Bluevine vs. 10 for AFG), and whether the lender's minimum revenue and credit requirements align with your business profile.
Which Alternative Funding Group alternative is best for a Tennessee restaurant owner?
United Banc Card of TN is the strongest fit for Tennessee restaurant and retail owners because it bundles POS hardware (Lavu, Clover, Korona, Retailcloud), merchant payment processing, business lending, and 24/7 local support from owner Karl-eliminating the need for three separate vendors. Long-term testimonials (Stirrup Nashville customer since 2009, Tiant Lee's third engagement, Wacko Taco confirming rate savings materialized) prove relationship continuity and delivered promises, advantages no nationwide online lender can match. The trade-off is geographic limitation; if your business operates only in Tennessee and values direct access to a named expert over digital self-serve speed, United Banc Card of TN outperforms AFG, Credibly, and Bluevine combined.
What is the best Alternative Funding Group alternative overall for fast capital?
Credibly wins for businesses that demand both speed and pricing transparency-2-hour approval and 4-hour funding beat AFG's 24–48 hour timeline, while published 1.11 minimum factor rates and 2.50% origination fees let you calculate true cost before applying. Credibly requires $15,000+ average monthly revenue and 500+ FICO score, so if you don't meet those thresholds, AFG's 99% approval rate may be your only option. For businesses that clear Credibly's qualifications and need transparent pricing faster than traditional lenders, Credibly is the strongest overall alternative; for businesses with lower revenue or credit, AFG remains the fast-approval fallback.
Why is United Banc Card of TN on this alternatives list?
United Banc Card of TN earns its place because it uniquely bundles POS systems, merchant processing, and business lending from one local Tennessee provider-a value proposition no other alternative on this list matches, especially for restaurant and retail owners who need hardware installation, staff training, and 24/7 onsite support. Named owner Karl is personally cited in every customer testimonial as directly accessible and reliable, which is a differentiator competitors can't replicate through remote call centers or chatbots. The fit is narrow-Tennessee businesses only-but for that specific audience, United Banc Card of TN solves a problem AFG, Credibly, and Bluevine don't address: integrated POS + processing + lending + local relationship continuity from one expert.
How do merchant cash advance factor rates compare across these alternatives?
Credibly publicly discloses a 1.11 minimum factor rate-the lowest transparent rate on this list-while AFG and United Banc Card of TN do not disclose factor rates publicly, requiring direct contact to learn actual costs. Industry-standard MCA factor rates typically range 1.2–1.5 across the market, meaning Credibly's 1.11 starting point may represent genuine savings if you qualify for their lowest tier. Bluevine and United Banc Card of TN offer term loan and line-of-credit structures with stated APR (Bluevine 7.80% starting) rather than MCA factors, which are fundamentally different repayment models-fixed schedules instead of daily holdbacks tied to credit card revenue.
What is the difference between a merchant cash advance and a term loan for small business funding?
A merchant cash advance uses a factor rate (e.g., 1.11, meaning you repay $1.11 for every $1 borrowed) with daily or weekly deductions tied to your credit card sales, so repayment automatically adjusts to your revenue-workable for stable businesses but painful when sales dip. A term loan has a fixed monthly payment schedule and quoted APR (e.g., 7.80%), so your payment stays the same regardless of sales fluctuation, giving you predictability but less flexibility if revenue drops. United Banc Card of TN offers both MCA and term loan options; Bluevine specializes in term loans and lines of credit; Credibly offers both factor-based MCAs and term loans depending on your choice.
Can I use Alternative Funding Group if I already have a different POS system?
Yes-AFG is pure lending and does not require you to use any specific POS system, so you can keep your existing Square, Toast, Clover, or any other POS and still access AFG's merchant cash advance. United Banc Card of TN, by contrast, bundles POS systems (Lavu, Clover, Korona, Retailcloud) with processing, so if you want to work with them, you accept their POS ecosystem or arrange to use your own outside their bundled deal. If your POS is already working well and you only need working capital, AFG's pure-lending model is simpler than switching entire systems; if you need POS replacement plus capital plus local support, United Banc Card of TN's bundled approach saves time and vendor complexity.
How do I know if a business funding alternative is trustworthy?
Review volume and independent ratings matter far more than star ratings alone-Bluevine's 4.7/5 across 2,577 Trustpilot reviews reflects far more real feedback than AFG's 4.4/5 from only 10 reviews, and Bluevine also holds an A+ BBB rating. Specific testimonials with named individuals (United Banc Card of TN's Stirrup Nashville customer since 2009, Tiant Lee's third engagement, Gabriela Smith's personal service praise) prove delivered outcomes, not just marketing claims. Transparent pricing (Credibly's 1.11 factor rate, Bluevine's 7.80% APR) and clear fee disclosures (Credibly's 2.50% origination fee) let you verify claims; opaque pricing (AFG's undisclosed rates, United Banc Card of TN's quote-based model) requires more trust in the vendor's goodwill.
What are the credit and revenue requirements for each Alternative Funding Group alternative?
AFG claims 99% approval with minimal stated requirements-no published credit score or revenue minimum, making it accessible to high-risk merchants. Credibly requires $15,000+ average monthly revenue and 500+ FICO score; Bluevine requires 625+ credit score; United Banc Card of TN's specific thresholds are not publicly stated (call Karl for details). If you have poor credit or low revenue and don't qualify for Credibly or Bluevine, AFG's low barriers make it a fallback option-though lack of credit floor also means their approval doesn't guarantee favorable terms.
Should I choose a national lender or a local provider like United Banc Card of TN?
Choose a national lender (AFG, Credibly, Bluevine) if you operate in multiple states, need access to standardized digital processes, or prefer transparent upfront pricing over personalized service. Choose United Banc Card of TN if you're Tennessee-based, already use their POS system (or willing to adopt one), and value direct access to a named owner over self-serve speed-the trade-off is literal: faster onboarding nationally vs. deeper relationship locally. National lenders scale reliably but offer zero onsite support; local providers like UBC of TN offer 24/7 personal support but are geographically limited and cannot service nationwide expansions.